

Wednesday, 07/10/2026, 12:11 (GMT +7)
 16
Around 12% of Global Containership Capacity Affected by Port Congestion
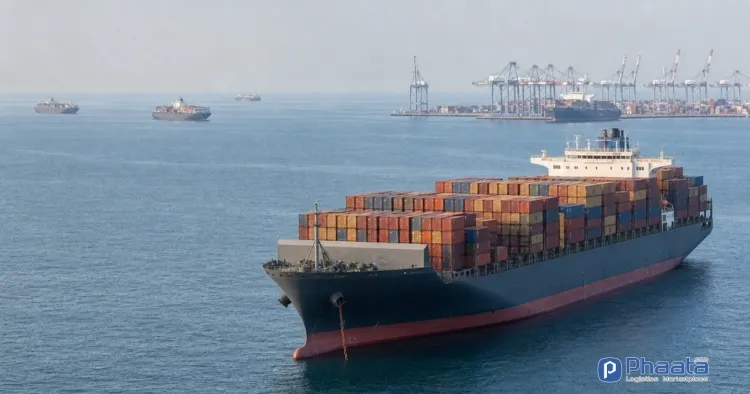
Vessel supply in the market remains available, but port congestion and schedule disruptions are reducing the amount of capacity that can actually be deployed.
According to C.H. Robinson’s October Edge Report, around 12% of global containership capacity is currently affected by port congestion, the highest level seen in the past four years. The impact is particularly evident in East Asia, Northern Europe and the Indian Subcontinent, reducing the amount of effective capacity accessible to shippers even though vessel capacity remains available in the market.
C.H. Robinson notes that published capacity across the ocean shipping network does not necessarily translate into capacity that is actually available. When vessels are delayed at ports or carriers adjust schedules to restore operations, the timing and location of capacity that can be effectively used also change.
“Capacity may exist in the ocean network, but port congestion and steps the carriers are taking to get schedules back on track can change where and when that capacity is actually available.”
Different Trends Across Trade Lanes in Early Q4
As the fourth quarter gets underway, the impact of congestion and schedule disruptions is becoming more evident across different trade lanes.
● Asia–North America: Capacity is being adjusted around China’s Golden Week holiday from October 1–7, while an expected recovery in cargo volumes after the holiday could continue to put pressure on vessel space.
● India–North America: Vessel space remains tight, while connections via Colombo continue to face disruptions.
● Asia–Europe: Freight rates are trending lower as vessel supply improves and some services begin returning to operations via the Suez Canal.
Schedule reliability has also deteriorated as port congestion, vessel bunching, tropical storms, developments in the Middle East and restrictions at the Panama Canal all affect carrier networks.
Port Omissions and Transshipment Disruptions Increase Risks
Recent storms in Asia have prompted some carriers to implement port omissions. Meanwhile, congestion at major transshipment hubs is disrupting connections, extending cargo handling times and increasing backlogs.
Containers sitting at congested ports are also making it more difficult to reposition empty equipment to markets where it is needed.
Notably, a port omission can cause greater disruption than a pre-planned blank sailing.
With a blank sailing, shippers can generally plan alternative options before cargo is delivered to the port. By contrast, when a carrier omits a port after a voyage has already begun, containers may have to wait for a feeder vessel, be routed through another transshipment hub or be rebooked onto an alternative service.
Asia–North America Faces Further Pressure After Golden Week
Pressure is becoming more apparent on the Asia–North America trade lane, where vessel space had already become tight ahead of Golden Week as exporters accelerated shipments before the holiday.
Meanwhile, blank sailings scheduled during the October 1–7 holiday are expected to continue reducing effective capacity through around mid-October. This could increase the risk of rollovers on the first departures after the holiday as factories resume operations and export volumes recover.
Developments after the holiday will be a key factor in determining how long tight space conditions persist. If cargo volumes rebound strongly, priority sailings could remain fully booked, supporting current freight rate levels. Conversely, if demand recovers more slowly, booking conditions could improve towards the end of October.
C.H. Robinson also notes that recent storms in Asia have disrupted operations at several major Chinese ports, resulting in vessel bunching, port omissions and changes to transshipment points. These effects could carry over into sailings after the holiday, depending on how quickly carriers clear backlogs and restore vessels to their planned operating rotations.
According to C.H. Robinson, the first sailings after Golden Week will be an important indicator of the direction of the Asia–North America market. If rollovers continue through mid-October, this would suggest that blank sailings, accumulated backlogs and the recovery in demand are still constraining effective capacity. Conversely, if these sailings clear more quickly, booking conditions could ease in the second half of October even if total published capacity changes little.
Nominal Capacity Does Not Fully Reflect Effective Capacity
Current market conditions show that the market cannot be assessed solely on the basis of total fleet capacity. More important is the amount of capacity that can actually be deployed and made available to shippers at any given time.
With around 12% of global containership capacity affected by port congestion, factors such as the choice of origin and destination ports, reliance on transshipment, empty container availability and carriers’ ability to restore schedules are becoming increasingly important to transport planning.
Therefore, when planning shipments in October, shippers should assess the entire transport journey, including connection points and contingency options when schedules change, rather than relying solely on the capacity published in sailing schedules.
See more:
- International Shipping and Logistics Market Update Week 40/2026 | Phaata
- CMA CGM Completes $1.4 Billion Acquisition of FedEx Supply Chain
- Legend Cargo Logistics: Eight Years of Building Expertise and Trust on the Vietnam–North America Trade Lane
- COSCO schedules: Vietnam - North America in Oct 2026
- COSCO updates Vietnam-North Europe sailing schedules in Oct 2026
- SITC updates Vietnam-Intra Asia sailing schedules in Oct 2026
- Sea-Intelligence: Global Schedule Reliability Falls to Lowest Level Since 2022
- Hapag-Lloyd Steps Up Talks with Israel, Details Revised ZIM Proposal
- IATA Calls for Stronger Controls on Dangerous Goods Across the Air Cargo Supply Chain
Source: Phaata.com (According to gCaptain)
► Find Better Freight Rates & Logistics Service Providers!


Featured News
- Hapag-Lloyd applies Peak Season Surcharge from East Asia to USA and Canada
- The world\'s largest container ships MSC Irina and MSC Loreto floated
- MSC (Mediterranean Shipping Company) - The world\'s leading container shipping lines
- Information you need to know about Maersk Line
- Top 10 export and import goods between Vietnam - Philippines in the first 5 months of 2020

 Market News
See more

 HOT PROMO
See more
80
 FCL
 6 Days
 Freight cost

N.B.L INTERNATIONAL TRANSPORT CO., LTD
315
FCL
30 Days
Freight cost
AIR TIGER EXPRESS LOGISTICS
791
FCL
23 Days
Freight cost

CÔNG TY TNHH TIẾP VẬN TOÀN CẦU KM
990
FCL
40 Days
Freight cost

CÔNG TY TNHH VẬN TẢI VÀ TIẾP VẬN TOÀN CẦU
1078
FCL
45 Days
Freight cost

Compass Logistics
 Premium
Why do thousands of businesses trust Phaata?
USERS/MONTH
LOGISTICS COMPANIES
REQUEST FOR QUOTEŚ
QUOTATIONS
VIETNAM LOGISTICS COMMUNITY
5 Steps to Get the Best Quote
Find a price quickly/Send a RFQ
Compare multiple options
Contact for Further Consultation
Negotiating prices/services
Management & rating
 Freight rates
Sea freight
- FCL
See more
22
25
Days Direct
- ₫150,839,100 / 20'GP
- ₫205,088,250 / 40'GP
- ₫205,088,250 / 40'HQ

OPL LOGISTICS
23
30
Days Transit
- ₫76,742,700 / 20'GP
- ₫83,358,450 / 40'GP
- ₫83,358,450 / 40'HQ
N.B.L INTERNATIONAL TRANSPORT CO., LTD
75
36
Days Direct
- ₫163,594,266 / 20'GP

CHI NHÁNH THÀNH PHỒ HỒ CHÍ MINH - CÔNG TY TNHH HECNY SHIPPING VIỆT NAM
97
40
Days Transit
- ₫258,014,250 / 40'HQ

CÔNG TY TRÁCH NHIỆM HỮU HẠN DT LOGISTICS (VN)
91
60
Days Direct
- ₫224,141,610 / 20'GP
- ₫283,154,100 / 40'GP
- ₫283,154,100 / 40'HQ
CÔNG TY TNHH SEAIR LINKS
Sea freight
- LCL
See more
391
4
Days Direct
- ₫0 /cbm
CÔNG TY CỔ PHẦN GIAO NHẬN VẬN TẢI HỒNG SƠN
615
5
Days Direct
- ₫0 /cbm
CÔNG TY TRÁCH NHIỆM HỮU HẠN DT LOGISTICS (VN)
1,087
6
Days Direct
- ₫523,180 /cbm
CÔNG TY TNHH VẬN TẢI VÀ TIẾP VẬN TOÀN CẦU
1,396
1,238
4
Days Direct
- ₫396,945 /cbm
CHI NHÁNH THÀNH PHỒ HỒ CHÍ MINH - CÔNG TY TNHH HECNY SHIPPING VIỆT NAM
 Air freight
- General cargo
See more
2,860
10
Days Transit
- 264,630 ₫/kg

Phoenix Logistics Vietnam - chi nhánh TP. Hồ Chí Minh (Phoenix International Forwarding Vietnam )
4,610
1
Days Direct
- 185,241 ₫/kg

CÔNG TY TNHH THƯƠNG MẠI VÀ DỊCH VỤ FASTRANS
7,740
 7,136
8
Days Transit
- 224,936 ₫/kg

CÔNG TY TNHH SEA GLOBAL VIỆT NAM
3,840
1
Days Direct
- 502,797 ₫/kg

CÔNG TY TNHH VẬN TẢI QUỐC TẾ GIA PHÚ
 Rail freight
- FCL
See more
1,173
5
Days Direct
- ₫44,987,100 / 40'HQ
- ₫44,987,100 / 45'HQ

CÔNG TY TNHH PHƯỚC TÁ
2,149
3
Days Direct
- ₫15,083,910 / 40'HQ
CÔNG TY CỔ PHẦN VẬN TẢI VÀ THƯƠNG MẠI ĐƯỜNG SẮT
12,837
7
Days Direct
- ₫48,956,550 / 20'GP

Công ty TNHH T&M Forwarding
11,844
5
Days Direct
- ₫7,145,010 / 20'GP
ASIAN EXPRESS LINE VIETNAM ( AEL VIET NAM )
9,136
10
Days Direct
- ₫9,262,050 / 20'GP

CÔNG TY CỔ PHẦN LOGISTICS QUỐC TẾ V&T
 Road freight
- FCL
See more
1,207
1
Day
- ₫28,000,000 / 20'GP
- ₫28,000,000 / 40'GP

CÔNG TY TNHH THƯƠNG MẠI DỊCH VỤ VÀ KHO VẬN VIETTEL POST - TTC
2,369
4
Day
- ₫211,704 / 20'GP

CÔNG TY CỔ PHẦN KINH DOANH THƯƠNG MẠI VÀ DỊCH VỤ HỎA TỐC
45,425
1
Day
- ₫6,868,686 / 20'OT
- ₫6,868,686 / 40'OT
- ₫6,868,686 / 40'OT HQ
CÔNG TY TNHH LIÊN VẬN QUỐC TẾ SHINING OCEAN VIỆT NAM
102,949
2
Day
- ₫6,500,000 / 40'RF
- ₫6,500,000 / 40'RQ
- ₫6,500,000 / 45'RQ

CÔNG TY CP PROSHIP
Premium
172,470
1
Day
- ₫18,997,200 / 20'GP
- ₫18,997,200 / 40'GP

CÔNG TY CỔ PHẦN GIAO NHẬN VẬN TẢI CON ONG


