


Sunday, 15/11/2026, 21:00 (GMT +7)
 19
International Shipping and Logistics Market Update Week 46/2026 | Phaata
International shipping and logistics market update - Week 46/2026
Table of Contents
-
World Container Index Week 46/2026
-
Asia - North America Ocean Freight Rates
-
Asia - Europe Ocean Freight Rates
-
Northern America - Asia Ocean Freight Rates
-
Northern Europe - Asia Ocean Freight Rates
-
Conclusions and Recommendations by Phaata
1. World Container Index Week 46/2026
Drewry’s World Container Index (WCI) for Week 46/2026 (from November 9 to November 15, 2026) decreased by 1.91% compared to the previous week, dropping to $4,305/FEU.
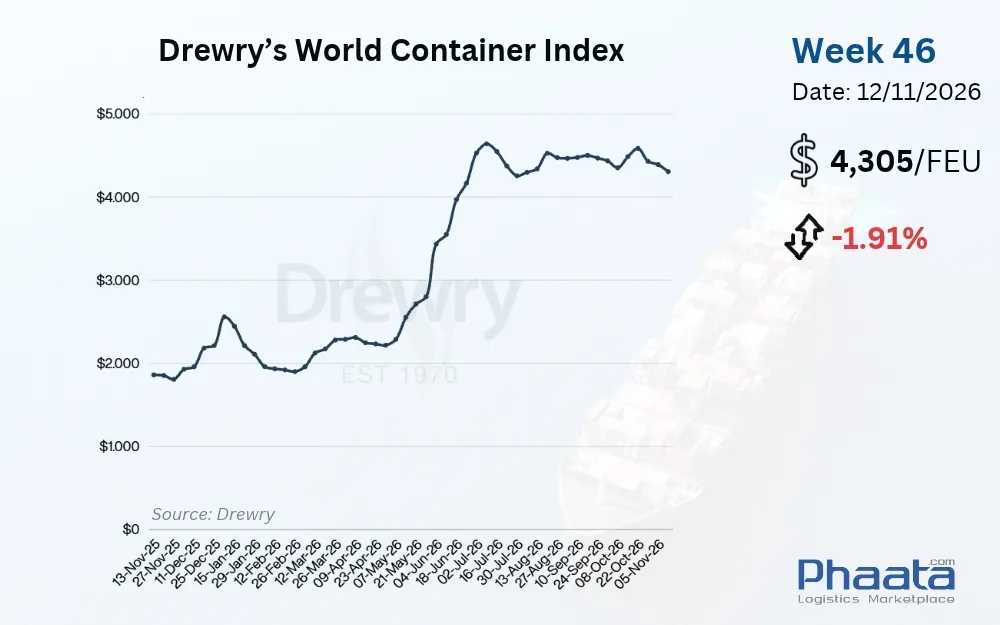
Drewry's World Container Index Week 46/2026 (Photo: Phaata)
2. Asia-North America Ocean Freight Rates
Supply and Demand:
High Operational Capacity Sustained: Carriers currently maintain operational levels at near 100% of design capacity. Capacity supply on the route is also being augmented by the deployment of larger-capacity vessels and the launch of a new direct service loop connecting China to the U.S. West Coast.
Cooling Demand and Capacity Adjustment Plans: The peak shipping season has passed. Forecasts indicate that U.S. import container volumes may continue to taper off through the end of the year, following a 12.6% year-over-year (YoY) surge recorded in September. Amid weakening demand, the blank sailing ratio currently sits at 2.3% and is projected to remain under 7% in the coming weeks, before spiking to approximately 9% the week of November 30. These capacity adjustments are seen as a strategic lever carriers use to balance capacity supply against market demand, thereby supporting rate baseline stability.
Asian Port Operations Improve: Congestion at several Chinese ports has eased significantly. At the Port of Shanghai, the average berth waiting time for mainline vessels is currently down to approximately 35 hours. This development contributes to improved operational conditions and supports vessel schedule reliability.
Operations:
Labor Situation at the Los Angeles – Long Beach (LA/LB) Port Complex: Operations at the LA/LB complex are drawing close attention amid ongoing labor negotiations. The labor agreement covering approximately 250 port security personnel at Los Angeles and Long Beach has been extended for a third time, now expiring November 20. Should a strike occur, port operations and cargo handling on the Asia-U.S. route could face disruptions.
Inland Transport Conditions: Inland cargo movement from ports continues to encounter hurdles due to rail delays and a shortage of container chassis at equipment depots. These factors can prolong container dwell times and disrupt delivery schedules in certain regions.
Rate Developments:
Ocean freight rates from Asia to the North America West Coast in Week 46/2026 increased slightly by 0.25% week-on-week, settling at $8,345/FEU. This rate is up 0.66% month-on-month, according to Xeneta data.
Freight Rates Show Signs of Correction: Although the rate baseline on both the U.S. West Coast and East Coast remains elevated compared to earlier periods, the recent upward momentum has stalled. Over the past week, Shanghai to Los Angeles spot rates remained virtually flat, while rates to New York on the East Coast dropped 3%. Concurrently, the benchmark SCFI index fell 1.5%, marking its first downward correction after four consecutive weeks of gains.
Developments Post-Nov 1 GRI: The market is transitioning into the slack season, while capacity supply remains relatively abundant. These factors are exerting downward pressure on the rate baseline in the short term. Consequently, the ability to sustain the November 1 General Rate Increase (GRI) implemented by carriers remains contingent upon demand dynamics and actual cargo volumes on the trade lane.
Stay tuned to Phaata International Logistics Marketplace for in-depth and fast market updates.
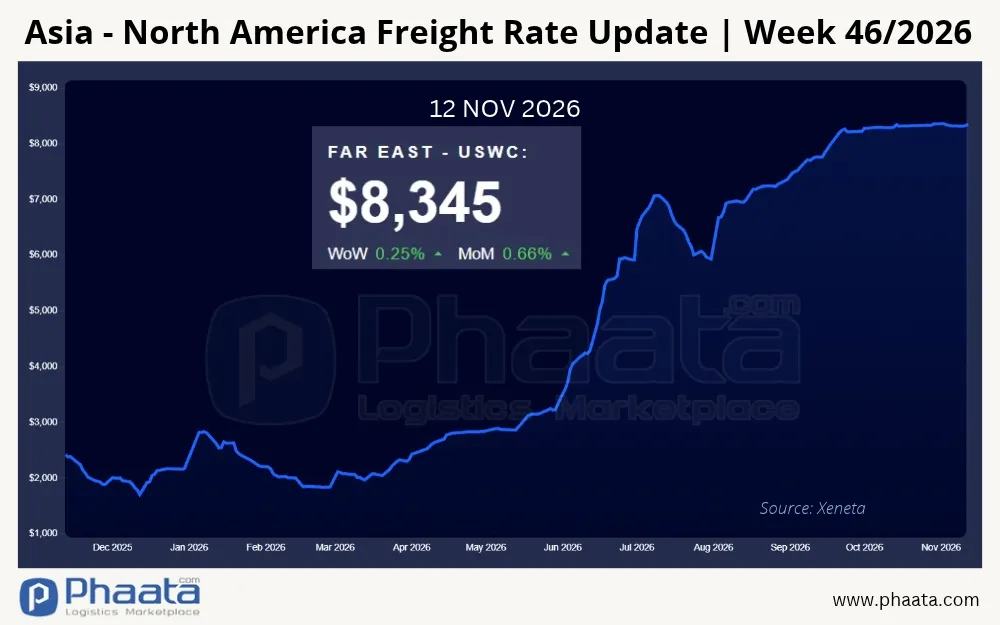
Asia-North America Freight Rates | Week 46/2026 (Photo: Phaata.com)
US Tariff Updates:
1. USTR Adjusts Deadlines for Section 301 Exemptions on Chinese Goods and Delays Vietnam IP Investigation The Office of the U.S. Trade Representative (USTR) recently announced deadline adjustments for several tariff and fee measures under Section 301, originally slated for changes in November 2026. Accordingly, the validity period for certain measures concerning China has been extended to January 2027, while the deadline for a final determination in the intellectual property (IP) investigation regarding Vietnam has been pushed to February 2027. Notable adjustments include:
-
Extension of Tariff Exemptions on Select Chinese Goods: The tariff exemption period for commodity lines under HTSUS codes 9903.88.69 and 9903.88.70 has been extended by an additional 60 days, running through January 9, 2027, superseding the prior November 9, 2026 deadline.
-
Note: During the exemption period update, U.S. Customs and Border Protection's (CBP) data processing systems may require additional time to synchronize information. Tariff application for entries filed during this transition will be governed by CBP’s updated guidelines and notices.
-
-
Fees on Ocean Vessels and Port Equipment: The suspension of fees on ocean vessels linked to China's shipbuilding industry, along with the deferred application of supplementary tariffs on ship-to-shore cranes and certain material handling equipment, has also been extended to January 9, 2027. These extensions unfold as the U.S. and China continue bilateral negotiations.
-
Intellectual Property Investigation in Vietnam: Regarding the investigation into intellectual property enforcement in Vietnam - initiated on May 29, 2026 - the USTR has delayed the final determination deadline by three months to February 28, 2027. The investigation remains under review, and trade measures may be considered pending the outcome.
-
Key Takeaway: The tariff exemption period for select Chinese goods now extends to January 9, 2027, while the referenced U.S.-China trade truce expires on January 10, 2027. The close proximity of these two dates marks a critical convergence in bilateral trade policy heading into early 2027.
2. CBP Clarifies U.S. IOR Status Requirements and Customs Broker Declaration Methods U.S. Customs and Border Protection (CBP) recently published a Frequently Asked Questions (FAQ) document concerning new regulations for Foreign Importers of Record (Foreign IORs), expected to take effect January 5, 2027. The document clarifies conditions for determining U.S. Importer of Record (U.S. IOR) status, declaration methods via Customs Brokers, and asset-related criteria for registering entities in the U.S. Key clarifications include:
-
Declarations via Customs Brokers: Foreign IORs not yet validated under the CTPAT program may still execute import procedures through a CTPAT-validated customs broker. According to the guidance, under standard circumstances, the broker can transmit the entry on behalf of the Foreign IOR without acting as the Importer of Record (IOR). However, if the foreign entity is neither the owner nor the purchaser of the shipment, the broker may be required to act as the IOR, subject to applicable conditions.
-
Note: The CTPAT validation process may involve on-site facility assessments. CBP's new guidance provides further details on broker-facilitated procedures for foreign entities that have not met this validation requirement.
-
-
Asset Criteria for 100% Foreign-Owned Entities: According to the guidance, a business lacking U.S. citizens or permanent residents as Beneficial Owners can still qualify for U.S. IOR status if it satisfies U.S. asset criteria. Specifically, the business must be incorporated in the U.S. and directly own domestic unencumbered tangible assets or real estate. The asset value must equal at least $20 million, or equivalent to the total value of the business's import entries in the preceding year, whichever is higher.
-
Determining Unencumbered Asset Value: Asset value is calculated after deducting debts secured by the asset itself. For example, U.S.-based machinery valued at $10,000 securing a $2,000 loan would have a calculated unencumbered asset value of $8,000 under this methodology.
-
Strategic Implication: CBP's new guidelines supplement information regarding U.S. IOR registration conditions and the role of customs brokers in the import process. These updates directly impact foreign businesses utilizing Delivered Duty Paid (DDP) terms or acting as the IOR when importing goods into the U.S. Clarifications on CTPAT validation, asset criteria, and party liabilities provide a firmer foundation for businesses and their customs partners to evaluate future import operational structures.
Stay tuned to articles on the Phaata International Logistics Marketplace for rapid and in-depth market updates.
3. Asia-Europe Ocean Freight Rates
Supply, Demand & Operations:
Blank Sailing Plan Developments: The blank sailing ratio on the route for Week 46 remains relatively low at approximately 3.6%. However, capacity adjustment plans for the ensuing weeks exhibit significant shifts. The blank sailing ratio is forecast to surge to 11% during the week of November 16, and hit roughly 18% during the week of December 7, while hovering below 8% for the remaining weeks. Carrier alliances continue to update sailing schedules, meaning actual cancellation rates may diverge from current plans.
Cargo Volume Trends on the Asia - Europe Route: Total cargo volume transported on the Asia - Europe corridor increased by 12.2% in the first seven months of the year. However, this growth may not fully capture current demand dynamics, as a portion of the volume likely stems from shippers front-loading orders to preempt year-end transport and trade uncertainties. Recently, export activity has shown signs of stalling, indicating that transport demand may cool in the upcoming phase.
Impact of Restoring Suez Canal Operations:
-
Red Sea Capacity Gradually Recovers: Carriers continue to adjust operational routings toward resuming transits via the Suez Canal. In October, weekly capacity routed through the Red Sea hit approximately 467,000 TEUs, equivalent to 50% of pre-crisis levels.
-
Capacity Supply Increases: Shortening vessel turnarounds - as certain services no longer detour via the Cape of Good Hope - contributed approximately 599,000 TEUs of nominal capacity in 2026. This capacity influx is expected to continue impacting the supply-demand balance through the first half of 2027. However, the pace of Suez route restoration and subsequent transit time adjustments still varies across carriers and services. Consequently, confirming actual operational routings remains a critical factor in transport planning.
Freight Rate Developments:
Ocean freight rates from Asia to Europe in Week 46/2026 decreased by 1.19% week-on-week, settling at $3,556/FEU. This rate is up 0.99% month-on-month, according to Xeneta data.
Spot Rates Begin to Correct: Following an upward trajectory since early October that peaked at a 15-week high on October 22, spot rates on the route are flashing signs of correction. The WCI index dropped 1% over the past week, marking its second consecutive week of decline. Specifically, the benchmark Shanghai - Rotterdam (Netherlands) leg recorded a 2% week-on-week (WoW) drop.
November GRI Developments: Carriers have announced General Rate Increases (GRIs) for the first half of November. However, the ongoing restoration of capacity via the Suez, coupled with the number of blank sailings slated to drop to 5 next week (down from 8 this week), may undermine the tenability of sustaining the new rate baseline. With capacity supply remaining relatively abundant, the efficacy of the GRI will depend heavily on demand dynamics and actual cargo volumes on the route.
Stay tuned to Phaata International Logistics Marketplace for in-depth and fast market updates.
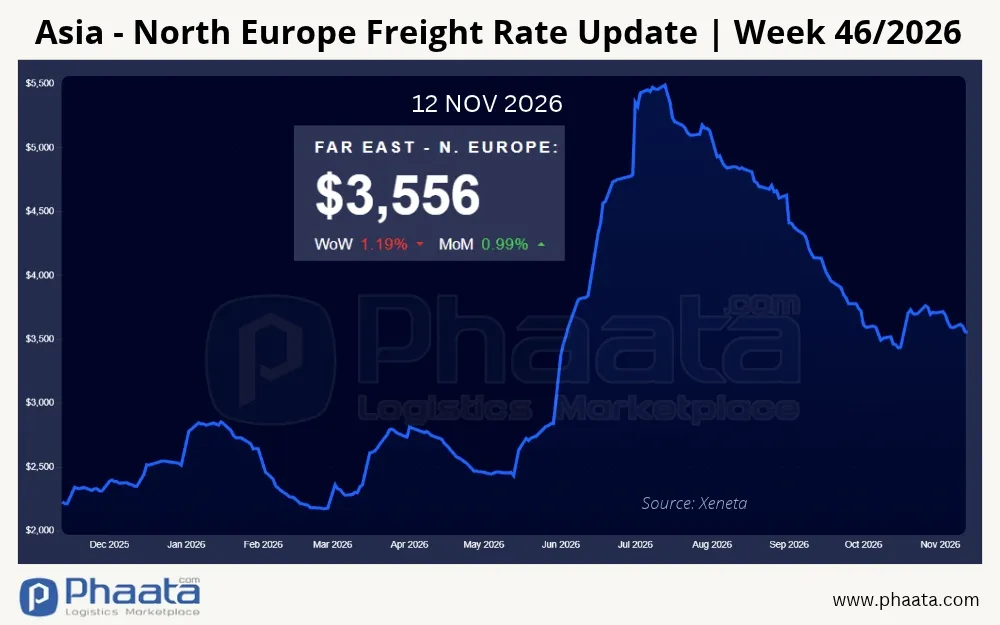
Asia-Europe Freight Rates | Week 46/2026 (Photo: Phaata.com)
4. North America - Asia Ocean Freight Rates
Ocean freight rates from North America (West Coast) to Asia in Week 46/2026 decreased by 0.56% week-on-week, settling at $708/FEU. This rate is up 6.63% month-on-month, according to Xeneta data.
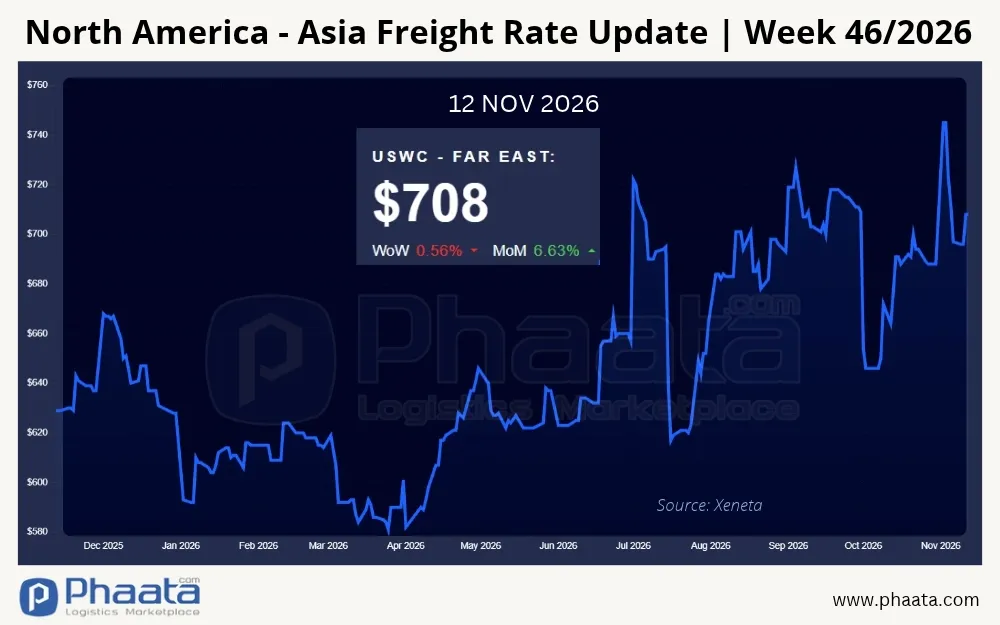
North America (West Coast) - Asia freight rates | Week 46/2026 (Photo: Phaata.com)
5. Northern Europe - Asia Ocean Freight Rates
Ocean freight rates from North Europe to Asia in Week 46/2026 decreased by 0.40% week-on-week, dropping to $252/FEU. This rate is up 8.62% month-on-month, per Xeneta data.
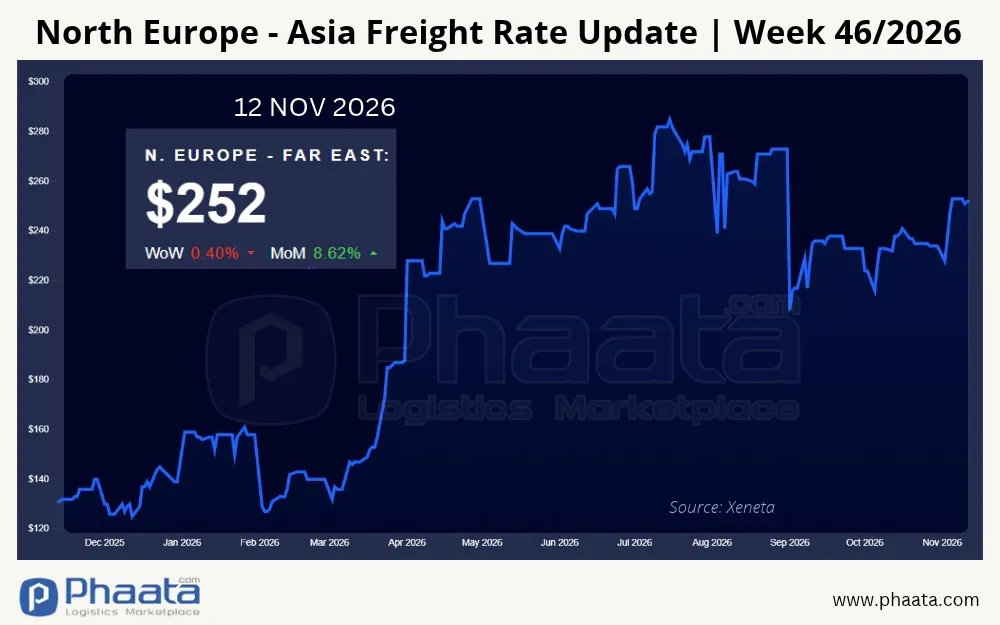
Container Freight rates from Northern Europe to Asia | Week 46/2026 (Photo: Phaata.com)
6. Conclusion and Recommendations from Phaata
The logistics market in Week 46/2026 recorded notable corrections as transport activity gradually transitions from peak to slack season, while carriers continue to adjust operational plans and routings. The Drewry WCI dropped 1.91% to $4,305/FEU, indicating that spot rates on major East-West trade lanes are showing signs of correction. This trend unfolds against a backdrop of cooling transport demand, whereas operational capacity on select routes remains relatively high.
Trans-Pacific Route (Asia - North America): Although freight rates remain elevated - with West Coast rates hitting $8,345/FEU - the market is stalling. The SCFI index fell 1.5%, reflecting a corrective shift in the spot market. The deployment of additional express loops, coupled with upsizing trends, could inflate capacity supply in the short term. Beyond rate developments, businesses must monitor operational factors in the U.S., particularly the labor situation at the LA/LB port complex- where the relevant labor agreement is set to expire on November 20 - and ongoing delays within the inland rail network.
Far East - West Europe Route: Transport operations via the Red Sea and Suez Canal are steadily recovering. In October, capacity routed through this region reached roughly 467,000 TEUs per week, or 50% of pre-crisis levels. Reverting to the Suez routing can shorten vessel turnarounds and contribute approximately 599,000 TEUs of nominal capacity in 2026, thereby boosting supply on the route. Amid signs of stalling demand, this supplementary supply is exerting downward pressure on rate tenability. Carriers continue to adjust operational plans, with blank sailing ratios projected to hit 18% in the first week of December.
U.S. Customs Policy and Compliance: Policy developments this week highlighted deadline adjustments and clarifications regarding compliance requirements:
-
The implementation deadline for several Section 301 tariff measures concerning Chinese goods and port equipment has been extended to January 9, 2027. This is a critical milestone for businesses to monitor, as the U.S.-China trade truce is slated to expire concurrently.
-
CBP continues to clarify declaration options for Foreign Importers of Record (Foreign IORs), including the use of Customs Brokers. Concurrently, CBP issued more precise guidelines regarding the unencumbered U.S. asset requirement for businesses seeking to register as a U.S. IOR independently.
Recommendations from Phaata
Cost of Goods Sold (COGS) & Space Management
-
Monitor and Negotiate Spot Rates: As the rate rally on the Trans-Pacific route stalls and capacity supply on the Far East - West Europe route is replenished, businesses should proactively benchmark quotes across multiple carriers and forwarders to strengthen negotiation leverage. For shipments scheduled for November, pay close attention to quote validity periods, applicable conditions, and the potential for carrier-announced GRI adjustments.
-
Factor in Buffer Time for Europe Routes: Schedule reliability on the route requires ongoing scrutiny, as on-time arrivals plummeted to a mere 4% in September. The concurrent use of Suez Canal and Cape of Good Hope routings by carriers can also lead to disparate transit times among voyages. Businesses should confirm the intended routing with carriers at the time of booking and allocate appropriate buffer time for cargo receipt, warehousing, and inland distribution in Europe.
Control Operational Risks and Customs Compliance
-
Monitor Labor Situation at the LA/LB Complex: For cargo bound for the U.S. West Coast, businesses should review export plans and Estimated Times of Arrival (ETA), particularly for time-sensitive shipments. For cargo moving deep inland via Interior Point Intermodal (IPI), coordinating early with road transport providers and confirming container chassis availability can mitigate the risk of delays, demurrage, and related costs.
-
Prepare Contingencies for Section 301 Tariffs: January 9, 2027, is a critical deadline that importers of Chinese goods must track closely. Businesses should construct landed cost scenarios accounting for the possibility that tariff measures are extended, adjusted, or expire after this date. Updating policy intelligence prior to cargo departure will enhance proactive cost planning.
-
Review Declaration Options for DDP (Delivered Duty Paid) Cargo: Foreign entities selling into the U.S. under DDP terms should collaborate with customs brokers to review declaration strategies compliant with CBP regulations. If CTPAT conditions are unmet or there is insufficient basis to independently register as a U.S. IOR, businesses must confirm the viability of utilizing a customs broker for declarations per current guidelines. For businesses aiming to act as the U.S. IOR independently, the preparation of documentation proving unencumbered assets and related conditions should be initiated promptly.
Stay tuned to articles on Phaata.com or Phaata fanpage for rapid and in-depth market updates.
Find Freight Rates Here
Find Logistics Companies Here
See more:
- U.S. and China officially extend trade truce by two months
- MSC increases December 2026 FAK rates on Far East–Mediterranean and Black Sea trades
- CMA CGM Announces New Peak Season Surcharges on Services from Asia to the Mediterranean and Mauritius
- COSCO Shipping Energy Plans 24-Vessel VLCC Fleet Expansion
- Evergreen's EVER EON Transits Suez Canal, Marking Return After Nearly Three Years of Disruption
- International Shipping and Logistics Market Update Week 45/2026 | Phaata
- MSC Extends PRS and SCS Coverage to All Mediterranean and Black Sea Ports
- Hapag-Lloyd Imposes US$400/TEU PSS on Cargo from Asia and Oceania to Tema
- Kuehne+Nagel Port Operations Update: Vessel Waiting Times in Ningbo and Shanghai Exceed Two Days
- BIMCO Releases Contract Addendum Establishing Framework for Sharing Costs and Benefits of Fuel-Saving Retrofits
- Hapag-Lloyd Implements $500/TEU Peak Season Surcharge on Asia and Oceania to South Africa Trades
- Over 35,000 Containers Await Rail Transport at the Los Angeles–Long Beach Port Complex
- THE NORTHWEST SEAPORT ALLIANCE HIGHLIGHTS TRANSPACIFIC GATEWAY ADVANTAGES AND INFRASTRUCTURE INVESTMENTS AT NOVEMBER 4 EXECUTIVE ROUNDTABLE IN HO CHI MINH CITY
- COSCO schedules: Vietnam - North America in Nov 2026
- COSCO updates Vietnam-North Europe sailing schedules in Nov 2026
- SITC updates Vietnam-Intra Asia sailing schedules in Nov 2026
Source: Phaata - Where Shippers & Logistics Providers Connect
► Find Better Freight Rates & Logistics Service Providers!


Featured News
- Hapag-Lloyd applies Peak Season Surcharge from East Asia to USA and Canada
- The world\'s largest container ships MSC Irina and MSC Loreto floated
- MSC (Mediterranean Shipping Company) - The world\'s leading container shipping lines
- Information you need to know about Maersk Line
- Top 10 export and import goods between Vietnam - Philippines in the first 5 months of 2020

 Market News
See more

 HOT PROMO
See more
26
 FCL
 10 Days
 Freight cost

NP LOGISTICS CO.,LTD
11260
FCL
35 Days
Freight cost
CÔNG TY TNHH CARDINAL GLOBAL LOGISTICS (VIETNAM)
 Premium
1661
FCL
15 Days
Freight cost

Compass Logistics
Premium
5249
FCL
38 Days
Freight cost
CHI NHÁNH THÀNH PHỒ HỒ CHÍ MINH - CÔNG TY TNHH HECNY SHIPPING VIỆT NAM
6947
 Other

INTERLOG CORP - CÔNG TY CỔ PHẦN GIAO NHẬN TIẾP VẬN QUỐC TẾ
Why do thousands of businesses trust Phaata?
USERS/MONTH
LOGISTICS COMPANIES
REQUEST FOR QUOTEŚ
QUOTATIONS
VIETNAM LOGISTICS COMMUNITY
5 Steps to Get the Best Quote
Find a price quickly/Send a RFQ
Compare multiple options
Contact for Further Consultation
Negotiating prices/services
Management & rating
 Freight rates
Sea freight
- FCL
See more
1
12
Days Direct
- ₫55,572,300 / 20'GP
- ₫59,541,750 / 40'HQ
Compass Logistics
Premium
572
3
Days Direct
- ₫3,175,560 / 20'GP
- ₫7,145,010 / 40'GP
- ₫7,145,010 / 40'HQ
GIA LINH LOGISTICS SERVICES CO., LTD. (G LINK Logistics)
545
6
Days Transit
- ₫14,554,650 / 20'GP
- ₫29,109,300 / 40'HQ
CÔNG TY TNHH GIAO NHẬN TOÀN CẦU GS
788
3
Days Direct
- ₫3,367,000 / 20'GP
- ₫7,252,000 / 40'GP
- ₫7,252,000 / 40'HQ
CÔNG TY CỔ PHẦN TIẾP VẬN INTERCARGO
835
3
Days Direct
- ₫1,323,150 / 20'GP

CÔNG TY TNHH VẬN CHUYỂN QUỐC TẾ TÂN TOÀN CẦU
Sea freight
- LCL
See more
659
12
Days Direct
- Refund ₫264,630 /cbm

CÔNG TY CỔ PHẦN SILVIET
1,004
 2,552
13
Days Direct
- ₫0 /cbm
CÔNG TY TNHH DỊCH VỤ VẬN TẢI BIỂN VESTAL
4,188
45
Days Transit
- Refund ₫131,570 /cbm
CÔNG TY TNHH LIÊN KẾT HOÀN HẢO (PERFECTLINK CO.,LTD)
5,913
7
Days Direct
- Refund ₫261,590 /cbm
CÔNG TY TNHH VẬN TẢI VÀ TIẾP VẬN TOÀN CẦU
 Air freight
- General cargo
See more
2,151
 10,749
1
Days Direct
- 46,310 ₫/kg

N.B.L INTERNATIONAL TRANSPORT CO., LTD
12,913
1
Days Direct
- 161,424 ₫/kg
CÔNG TY CỔ PHẦN GIAO NHẬN VẬN TẢI HỒNG SƠN
15,245
10
Days Transit
- 264,630 ₫/kg
Phoenix Logistics Vietnam - chi nhánh TP. Hồ Chí Minh (Phoenix International Forwarding Vietnam )
14,593
1
Days Direct
- 185,241 ₫/kg
CÔNG TY TNHH THƯƠNG MẠI VÀ DỊCH VỤ FASTRANS
 Rail freight
- FCL
See more
11,642
5
Days Direct
- ₫44,987,100 / 40'HQ
- ₫44,987,100 / 45'HQ
CÔNG TY TNHH PHƯỚC TÁ
15,165
3
Days Direct
- ₫15,083,910 / 40'HQ
CÔNG TY CỔ PHẦN VẬN TẢI VÀ THƯƠNG MẠI ĐƯỜNG SẮT
24,752
7
Days Direct
- ₫48,956,550 / 20'GP
Công ty TNHH T&M Forwarding
23,207
5
Days Direct
- ₫7,145,010 / 20'GP
ASIAN EXPRESS LINE VIETNAM ( AEL VIET NAM )
11,857
10
Days Direct
- ₫9,262,050 / 20'GP

CÔNG TY CỔ PHẦN LOGISTICS QUỐC TẾ V&T
 Road freight
- FCL
See more
552
6
Hour
- ₫10,500,000 / 40'GP
- ₫10,500,000 / 40'HQ
Công ty TNHH Giao nhận quốc tế HP LINK
607
 16,932
1
Day
- ₫28,000,000 / 20'GP
- ₫28,000,000 / 40'GP
CÔNG TY TNHH THƯƠNG MẠI DỊCH VỤ VÀ KHO VẬN VIETTEL POST - TTC
117,655
2
Day
- ₫6,500,000 / 40'RF
- ₫6,500,000 / 40'RQ
- ₫6,500,000 / 45'RQ

CÔNG TY CP PROSHIP
Premium
184,152
1
Day
- ₫18,997,200 / 20'GP
- ₫18,997,200 / 40'GP

CÔNG TY CỔ PHẦN GIAO NHẬN VẬN TẢI CON ONG


