

Friday, 15/05/2026, 13:07 (GMT +7)
 599
Trans-Pacific Freight Rates Remain Elevated Amid Muted Demand
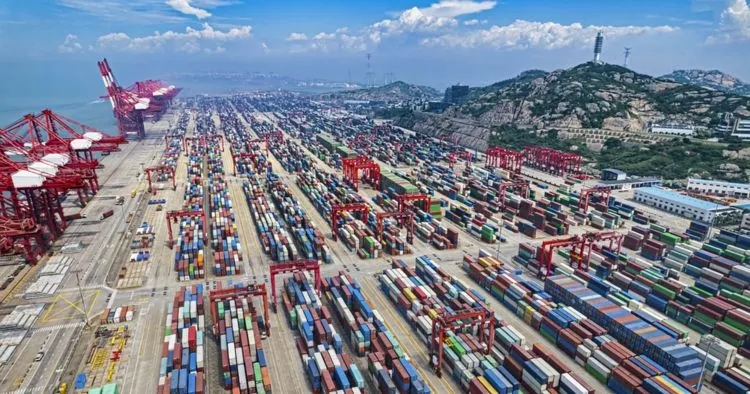
Freight rates on major trade lanes from Asia to the US are still substantially higher than before the Iran tensions escalated in late February. However, rather than being demand-driven, the current price levels are largely being "propped up" by ocean carriers' capacity reduction strategies.
Capacity Management Continues to Prop Up Rates
The latest data from the Freightos Baltic Index shows that average weekly rates on the trans-Pacific are currently about $1,000/FEU (forty-foot equivalent unit) higher than in the pre-conflict period.
For the week ending May 8, Asia-US West Coast (USWC) rates rose by 4% to $2,828/FEU. Meanwhile, the Asia-US East Coast (USEC) lane saw a slight increase of 1%, reaching $4,340/FEU.
In contrast to the trend on the trans-Pacific, the Asia-Europe market is showing signs of cooling down. Judah Levine, Head of Research at Freightos (NASDAQ: CRGO), noted in his latest research report: "Asia-Europe rates, which had gained a few hundred dollars per FEU in March, have now largely reverted to pre-conflict levels."
Spot rates on the Asia-North Europe route increased by 10% last week to $2,850/FEU. However, a downward trend has begun to emerge this week, mirroring the developments seen on the Mediterranean trade lane earlier this month.
To counter weakening demand, shipping lines are stepping up their supply-tightening strategies through blank sailings and capacity adjustments. According to Levine: "Carriers are planning further rate increases, albeit likely modest ones, for mid-month."
Concurrently, the number of canceled sailings continues to rise amid multiple reports of space shortages emerging on several East-West trade lanes. Furthermore, many confirmed container bookings are being rolled to subsequent voyages due to capacity constraints.
This is seen as a clear effort by carriers to protect spot rate levels during the slack season, while also preparing for the anticipated rebound in shipping demand during the year-end peak season.
Hormuz Risks Continue to Exert Pressure
Carriers' price-supporting measures are taking place against a backdrop of geopolitical risks in the Middle East that have yet to cool down.
According to Levine, Washington and Tehran have resumed military posturing around the Strait of Hormuz after the US paused its commercial vessel escort operation less than two days after its initial deployment.
On Iran's side, the country announced the establishment of the Persian Gulf Strait Authority (PGSA) to coordinate traffic through this strategic maritime route. Meanwhile, observers are still monitoring whether dialogues in Beijing between US President Donald Trump and Chinese President Xi Jinping could yield any significant impact on the regional landscape.
Cost pressures from the Hormuz flashpoint remain massive. In its Q1 earnings report, Maersk stated that disruptions in the region are incurring approximately $500 million in additional costs per month—an expense that has already been partially passed down into freight rates.
Some industry experts also warn that in the near future, the pressing concern will not just be fuel prices, but the actual accessibility of bunker fuel supplies to operate the fleets.
Recovery Outlook Still Lacks Momentum
On the demand side, the US consumer market has yet to emit many positive signals.
Citing the National Retail Federation's (NRF) projection of a rather muted peak season on the trans-Pacific, Levine stated: "June volumes are projected to be 2% lower than May, while July is expected to increase by only about 4% before weakening again."
According to him, this reflects the cautious sentiment of importers amid stubbornly high fuel costs and an unclear consumer outlook for the second half of the year.
Overall, the short-term container shipping market is likely to remain in a tug-of-war between aggressive capacity management measures by carriers on one side and hesitant import demand on the other. In this context, the risks of fuel cost volatility and geopolitical tensions will continue to be factors capable of heavily impacting global freight rates.
See more:
- CMA CGM Implements Peak Season Surcharge from South China and Hong Kong
- Maersk: Iran War is Adding $500 Million in Costs per Month - And Customers Will Have to Shoulder a Portion
- International Shipping and Logistics Market Update Week 19/2026 | Phaata
- Hormuz Traffic in Freefall: Iran Tightens Its Grip as the World Waits to See What 'Reopening' Really Means
- Yang Ming Expands Far East - Latin America Service Network Through Agreements with HMM and ONE
- Maersk Q1 2026: Solid Growth Despite Freight Rate Pressures and Geopolitical Instability
- Shipping Lines Adrift in Uncertainty: When Will the Strait of Hormuz Truly Reopen?
- Global Schedule Reliability Hits Year-to-Date High in March 2026
- Two US Destroyers Enter the Persian Gulf, Washington Declares Absolute Control Over the Strait of Hormuz
- Middle East Pressure: Maersk Shifts to Weekly Fuel Surcharge Mechanism in Three European Countries
- Trans-Pacific Trade: The Exodus of Non-Alliance Carriers
- The North European Port Paradox: When Opting for 'Mega-Ports' No Longer Guarantees Schedule Reliability
- International Shipping and Logistics Market Update Week 18/2026 | Phaata
- COSCO schedules: Vietnam - North America in May 2026
- COSCO updates Vietnam-Intra Asia sailing schedules in May 2026
- COSCO updates Vietnam-North Europe sailing schedules in May 2026
- COSCO updates sailing schedules of Vietnam - South America & Africa in May 2026
- COSCO updates sailing schedules of Vietnam-Middle East & Oceania in May 2026
- SITC updates Vietnam-Intra Asia sailing schedules in May 2026
Source: Phaata.com (According to Freight Waves)
► Find Better Freight Rates & Logistics Service Providers!


Featured News
- Hapag-Lloyd applies Peak Season Surcharge from East Asia to USA and Canada
- The world\'s largest container ships MSC Irina and MSC Loreto floated
- MSC (Mediterranean Shipping Company) - The world\'s leading container shipping lines
- Information you need to know about Maersk Line
- Top 10 export and import goods between Vietnam - Philippines in the first 5 months of 2020

 Market News
See more


 HOT PROMO
See more
274
 FCL
 50 Days
 Freight cost

Compass Logistics
 Premium
1613
FCL
23 Days
Freight cost

CÔNG TY TNHH TIẾP VẬN TOÀN CẦU KM
5775
FCL
3 Days
Freight cost
.webp)
GAMA INTERNATIONAL CORPORATION
7439
 Other

INTERLOG CORP - CÔNG TY CỔ PHẦN GIAO NHẬN TIẾP VẬN QUỐC TẾ
6799
FCL
25 Days
Freight cost

CÔNG TY TNHH LBS LOGISTICS
Why do thousands of businesses trust Phaata?
USERS/MONTH
LOGISTICS COMPANIES
REQUEST FOR QUOTEŚ
QUOTATIONS
VIETNAM LOGISTICS COMMUNITY
5 Steps to Get the Best Quote
Find a price quickly/Send a RFQ
Compare multiple options
Contact for Further Consultation
Negotiating prices/services
Management & rating
 Freight rates
Sea freight
- FCL
See more
65
6
Days Direct
- ₫13,760,760 / 20'GP
- ₫29,638,560 / 40'GP
- ₫29,638,560 / 40'HQ

CÔNG TY CỔ PHẦN TIẾP VẬN INTERCARGO
119
35
Days Direct
- ₫52,926,000 / 20'GP
- ₫79,389,000 / 40'HQ

Cardinal Global Logistics
Premium
246
297
7
Days Direct
- ₫3,969,450 / 20'GP
- ₫9,262,050 / 40'GP

CÔNG TY CỔ PHẦN LOGISTICS VINALINK
268
4
Days Direct
- ₫33,078,750 / 40'GP

KHAI MINH GROUPS CO., LTD – Ho Chi Minh Branch
Sea freight
- LCL
See more
155
4
Days Direct
- ₫26,463 /cbm

CÔNG TY TNHH IEC EXPRESS (VIỆT NAM)- CHI NHÁNH HÀ NỘI
315
5
Days Direct
- ₫26,463 /cbm

CHI NHÁNH TẠI THÀNH PHỐ HỒ CHÍ MINH - CÔNG TY CỔ PHẦN MG LOGISTICS
1,200
8
Days Direct
- Refund ₫2,362,500 /cbm
CÔNG TY CỔ PHẦN TIẾP VẬN INTERCARGO
1,903
4
Days Direct
- ₫26,463 /cbm

CÔNG TY CỔ PHẦN GIAO NHẬN VẬN TẢI MỸ Á (ASL LOGISTICS)
3,192

 Air freight
- General cargo
See more
311
1
Days Direct
- 185,241 ₫/kg

CÔNG TY TNHH THƯƠNG MẠI VÀ DỊCH VỤ FASTRANS
1,427
5
Days Transit
- 224,936 ₫/kg

CÔNG TY TRÁCH NHIỆM HỮU HẠN DT LOGISTICS (VN)
4,012
 5,020
4
Days Transit
- 357,251 ₫/kg

Phoenix Logistics Vietnam - chi nhánh TP. Hồ Chí Minh (Phoenix International Forwarding Vietnam )
4,377
8
Days Transit
- 224,936 ₫/kg

CÔNG TY TNHH SEA GLOBAL VIỆT NAM
 Rail freight
- FCL
See more
125
4
Days Direct
- ₫11,802,498 / 40'HQ
CÔNG TY CỔ PHẦN VẬN TẢI VÀ THƯƠNG MẠI ĐƯỜNG SẮT
1,269
4
Days Direct
- ₫22,361,235 / 40'HQ
- ₫22,361,235 / 45'HQ

CÔNG TY TNHH PHƯỚC TÁ
9,179
7
Days Direct
- ₫48,956,550 / 20'GP

Công ty TNHH T&M Forwarding
8,700
5
Days Direct
- ₫7,145,010 / 20'GP
ASIAN EXPRESS LINE VIETNAM ( AEL VIET NAM )
7,809
10
Days Direct
- ₫9,262,050 / 20'GP

CÔNG TY CỔ PHẦN LOGISTICS QUỐC TẾ V&T
 Road freight
- FCL
See more
41,541
1
Day
- ₫6,868,686 / 20'OT
- ₫6,868,686 / 40'OT
- ₫6,868,686 / 40'OT HQ

CÔNG TY TNHH VẬN TẢI BẢO KHANG
97,735
2
Day
- ₫6,500,000 / 40'RF
- ₫6,500,000 / 40'RQ
- ₫6,500,000 / 45'RQ

CÔNG TY CP PROSHIP
Premium
168,261
1
Day
- ₫18,997,200 / 20'GP
- ₫18,997,200 / 40'GP

CÔNG TY CỔ PHẦN GIAO NHẬN VẬN TẢI CON ONG
260,693
3
Day
- ₫32,000,000 / 20'GP
- ₫64,000,000 / 40'GP
- ₫64,000,000 / 40'HQ
- ₫64,000,000 / 45'HQ

Công ty Cổ phần phát triển thương mại Thuận Đạt Việt Nam
281,896


