


Thursday, 30/04/2026, 11:00 (GMT +7)
 506
Two Months of Hormuz Closure: A Mixed Picture for the Liquid Bulk Market
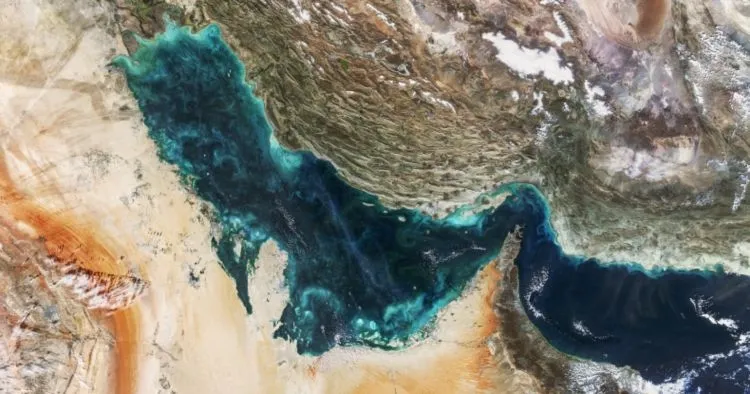
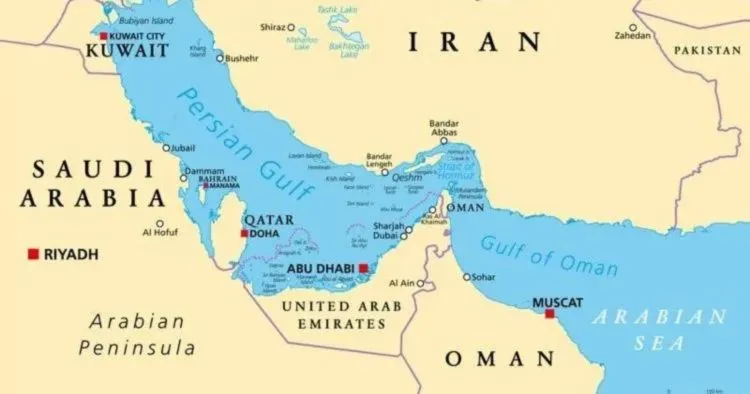
The Strait of Hormuz has been effectively closed for the past two months with no signs of returning to normalcy anytime soon. All segments across the liquid bulk shipping market have been heavily impacted, but the volatility of spot freight rates is diverging into vastly different scenarios.
To assess this divergence, maritime research firm Lloyd’s List compared the index change rates across four main segments: Very Large Crude Carriers (VLCC), midsize crude tankers, product tankers, and Liquefied Petroleum Gas (LPG) carriers.
Under a typical geopolitical disruption model, freight rates experience an initial panic-driven spike, followed by a pullback. However, the current scenario is proving to be much more complex.
Very Large Crude Carriers: Cooling Down After the Fever
The current rate pattern for VLCCs mirrors the early days of the Russia-Ukraine war, where small and midsize tankers recorded better performance than VLCCs.
The Baltic Exchange’s time charter equivalent (TCE) index for VLCCs on the West Africa-to-China route has surged 150% since mid-February. It peaked on March 3, touching $275,369/day. However, this level quickly plummeted as many VLCCs repositioned to the Atlantic basin and market sentiment cooled.
Since mid-March, the index has stabilized around the $100,000/day mark.
Midsize Crude Tankers: Outstanding Growth
In stark contrast to VLCCs, the Baltic Exchange’s Suezmax index (averaging the Black Sea-to-Mediterranean and West Africa-to-North Europe routes) did not pull back in mid-March but continued to climb sharply until the end of last month.
The Suezmax index peaked on March 26 at $279,748/day, a 200% increase compared to mid-February, before sliding in April. Nevertheless, as of now, rates remain 28% higher than pre-war levels.
Midsize crude tanker rates are being strongly supported by massive crude export volumes from the US to Europe, primarily via Aframax vessels, as well as long-haul voyages from the Atlantic to Asia through the Panama Canal's Panamax locks.
Product Tankers: The Best Performers
While midsize crude tankers outpaced VLCCs, product tankers recorded an even more impressive performance.
The Baltic-published Atlantic basin index for Medium Range (MR) and Handysize tankers only peaked in mid-April. Atlantic route rates experienced a threefold surge, climbing from $35,000/day in mid-February to a record peak of $112,755/day on April 13. By last Thursday, although the rate had retreated to the $75,366/day threshold, it was still practically double the pre-war level and up a staggering 193% year-over-year (YoY).
The primary drivers are robust demand for diesel, gasoline, and jet fuel across Europe, South America, Africa, and Asia, compounded by longer voyage distances.
Very Large Gas Carriers: An Upstream Comeback Driven by Bottlenecks
The VLGC segment paints an entirely different trajectory. Using US LPG supplies to offset the shortfall from the Middle East Gulf (MEG) is impossible due to terminal capacity constraints in the US Gulf. In theory, this leads to an oversupply of tonnage (many VLGCs but scarce cargo).
Initially, the US Gulf-to-Japan VLGC index plummeted following the outbreak of the conflict, dropping from around $75,000/day to $38,171/day on March 11. But an unexpected twist occurred: from the second half of March through April, US Gulf VLGC rates staged a sharp recovery.
By last Thursday, the index hit $142,889/day (more than triple the pre-war rate and up 276% YoY)—the highest TCE rate since the Panama Canal drought crisis in September 2023.
Explaining this incredible rebound, Clarksons Securities pointed to widening arbitrage—the price spread between US Mont Belvieu propane and Asian prices expanded from $250 to $300/ton—and market inefficiencies.
In its report, Clarksons highlighted a localized vessel shortage: "A significant portion of the [VLGC] fleet has traditionally focused exclusively on the Middle East market and has not previously carried US cargoes, meaning [the ships] did not have US Coast Guard approval for US loading."
"This application process is understood to take at least five to six weeks, which has limited VLGCs that would otherwise be available because of limited Middle East export flows."
"It is unclear how many VLGCs have applied for US Coast Guard approval, but some estimates suggest that as many as 50 have applied."
Furthermore, capacity limits at the Neopanamax locks (Panama Canal) are becoming a major hurdle. Mega containerships are dominating transit traffic, pushing waiting times for unbooked vessels to an average of 7.9 days southbound (Atlantic to Pacific).
Consequently, canal transit slot auction prices have exploded. According to Argus, the average auction price at the Neopanamax locks reached $1.7 million during the week ending April 17, the highest weekly average since Argus began collecting this data in January 2024. Notably, one April auction slot hit $4 million (matching the record high seen during the November 2023 drought period).
In summary: The supply chain is stretched to its absolute limit. Increasing volumes of US LPG are being forced to take the longer route around the Cape of Good Hope. The voyage from Houston to Japan via the Panama Canal is already 43% longer than the MEG-to-Japan route; taking the Cape of Good Hope extends this distance to 2.4 times longer.
See more:
- China Launches World's Largest Electric Container Ship: A Decarbonization Milestone for the Maritime Industry
- Hapag-Lloyd Implements New Emergency Surcharge on Southern Europe Feeder Routes Amid Cost Pressures
- COSCO schedules: Vietnam - North America in May 2026
- COSCO updates Vietnam-Intra Asia sailing schedules in May 2026
- COSCO updates Vietnam-North Europe sailing schedules in May 2026
- COSCO updates sailing schedules of Vietnam - South America & Africa in May 2026
- COSCO updates sailing schedules of Vietnam-Middle East & Oceania in May 2026
- UNCTAD and Singapore Partner to Drive Sustainable Maritime Transition
- International Shipping and Logistics Market Update Week 17/2026 | Phaata
- SITC updates Vietnam-Intra Asia sailing schedules in May 2026
- COSCO Shipping and Sepetiba Tecon Sign 10-Year Agreement: Elevating the Brazil-China Trade Route
- Ocean Freight Surcharges Soar Amid Hormuz Crisis: Massive Pressure on Contract Negotiation Season
- IMO Tightens Ship Registration Guidelines Amid a Wave of Fraudulent Flagging
- Hormuz Crisis: Top Global Shipping Lines Demand Absolute Guarantees of Safe Passage
- Hormuz Tensions: IRGC Claims Seizure of Two MSC Containerships in Retaliation Against US
- CMA CGM Announces FAK Rate Increase on the Asia-Mediterranean Trade Lane Starting May 2026
Source: Phaata.com (According to Lloyd's List)
► Find Better Freight Rates & Logistics Service Providers!


Featured News
- Hapag-Lloyd applies Peak Season Surcharge from East Asia to USA and Canada
- The world\'s largest container ships MSC Irina and MSC Loreto floated
- MSC (Mediterranean Shipping Company) - The world\'s leading container shipping lines
- Information you need to know about Maersk Line
- Top 10 export and import goods between Vietnam - Philippines in the first 5 months of 2020

 Market News
See more






 HOT PROMO
See more
507
 FCL
 30 Days
 Freight cost

CÔNG TY TNHH PEGASHIP
2117
FCL
45 Days
Freight cost

Compass Logistics
 Premium
3726
FCL
30 Days
Freight cost

CÔNG TY TNHH INTERNATIONAL LOGISTICS GLORY (VIỆT NAM)
5278
FCL
3 Days
Freight cost

Công ty TNHH Giao nhận vận chuyển Quốc tế Trường Hải - THILOGI
Premium
4781
FCL
10 Days
Freight cost
CÔNG TY TNHH THƯƠNG MẠI VÀ DỊCH VỤ GREEN DRAGON VIỆT NAM
Why do thousands of businesses trust Phaata?
USERS/MONTH
LOGISTICS COMPANIES
REQUEST FOR QUOTEŚ
QUOTATIONS
VIETNAM LOGISTICS COMMUNITY
5 Steps to Get the Best Quote
Find a price quickly/Send a RFQ
Compare multiple options
Contact for Further Consultation
Negotiating prices/services
Management & rating
 Freight rates
Sea freight
- FCL
See more
139
6
Days Direct
- ₫35,725,050 / 40'HQ
CÔNG TY TNHH ENSIGN LOGISTICS (VIỆT NAM)
252
7
Days Direct
- ₫41,149,700 / 40'HQ
CÔNG TY TNHH DNLSHIPPING CORPORATION
283
 429
5
Days Direct
- ₫39,694,500 / 40'HQ
CÔNG TY TNHH VẬN CHUYỂN QUỐC TẾ TÂN TOÀN CẦU
442
7
Days Direct
- ₫40,223,760 / 40'HQ

CÔNG TY TRÁCH NHIỆM HỮU HẠN DT LOGISTICS (VN)
Sea freight
- LCL
See more
2,129
4
Days Direct
- ₫26,463 /cbm

CÔNG TY TNHH IEC EXPRESS (VIỆT NAM)- CHI NHÁNH HÀ NỘI
3,270
5
Days Direct
- ₫26,463 /cbm

CHI NHÁNH TẠI THÀNH PHỐ HỒ CHÍ MINH - CÔNG TY CỔ PHẦN MG LOGISTICS
3,866
8
Days Direct
- Refund ₫2,362,500 /cbm

CÔNG TY CỔ PHẦN TIẾP VẬN INTERCARGO
4,413
4
Days Direct
- ₫26,463 /cbm

CÔNG TY CỔ PHẦN GIAO NHẬN VẬN TẢI MỸ Á (ASL LOGISTICS)
4,361

 Air freight
- General cargo
See more
1,158
10
Days Transit
- 264,630 ₫/kg

Phoenix Logistics Vietnam - chi nhánh TP. Hồ Chí Minh (Phoenix International Forwarding Vietnam )
1,933
1
Days Direct
- 185,241 ₫/kg

CÔNG TY TNHH THƯƠNG MẠI VÀ DỊCH VỤ FASTRANS
5,407
 5,073
8
Days Transit
- 224,936 ₫/kg

CÔNG TY TNHH SEA GLOBAL VIỆT NAM
2,834
1
Days Direct
- 502,797 ₫/kg

CÔNG TY TNHH VẬN TẢI QUỐC TẾ GIA PHÚ
 Rail freight
- FCL
See more
888
5
Days Direct
- ₫26,463,000 / 40'HQ
- ₫26,463,000 / 45'HQ

CÔNG TY TNHH PHƯỚC TÁ
1,282
3
Days Direct
- ₫6,324,657 / 40'HQ

CÔNG TY CỔ PHẦN VẬN TẢI VÀ THƯƠNG MẠI ĐƯỜNG SẮT
10,578
7
Days Direct
- ₫48,956,550 / 20'GP

Công ty TNHH T&M Forwarding
9,930
5
Days Direct
- ₫7,145,010 / 20'GP

ASIAN EXPRESS LINE VIETNAM ( AEL VIET NAM )
8,256
10
Days Direct
- ₫9,262,050 / 20'GP

CÔNG TY CỔ PHẦN LOGISTICS QUỐC TẾ V&T
 Road freight
- FCL
See more
42,742
1
Day
- ₫6,868,686 / 20'OT
- ₫6,868,686 / 40'OT
- ₫6,868,686 / 40'OT HQ

CÔNG TY TNHH LIÊN VẬN QUỐC TẾ SHINING OCEAN VIỆT NAM
100,043
2
Day
- ₫6,500,000 / 40'RF
- ₫6,500,000 / 40'RQ
- ₫6,500,000 / 45'RQ

CÔNG TY CP PROSHIP
Premium
170,280
1
Day
- ₫18,997,200 / 20'GP
- ₫18,997,200 / 40'GP

CÔNG TY CỔ PHẦN GIAO NHẬN VẬN TẢI CON ONG
262,602
3
Day
- ₫32,000,000 / 20'GP
- ₫64,000,000 / 40'GP
- ₫64,000,000 / 40'HQ
- ₫64,000,000 / 45'HQ

Công ty Cổ phần phát triển thương mại Thuận Đạt Việt Nam
283,248


