

Wednesday, 21/10/2026, 11:15 (GMT +7)
 26
Container Shipping Networks: A Shift Away from Shared Capacity Among Carriers
Source: Freepik
The global container shipping industry is undergoing changes in the way service networks are organized. While the number of services continues to increase, fewer carriers are offering space on each service. This trend indicates a shift in the extent of capacity sharing among carriers and could lead to greater differences in sailing schedules and service connection options.
Vessel Sharing Agreements and Limitations in Service Choice
Before 2017, international container shipping networks relied heavily on cooperation agreements between carriers. Through Vessel Sharing Agreements (VSAs), carriers jointly operated vessels and allocated capacity, enabling them to maintain broad service coverage without having to independently organize all vessel operations on every trade lane.
This model allowed carriers to expand their networks and use capacity more efficiently. However, when multiple carriers participated in the same service, each could market space under its own brand despite sharing vessels and sailing schedules. As a result, the number of options visible to shippers in the market did not necessarily reflect the actual differences between available shipping services.
Expanding Networks, Fewer Carriers Sharing Each Service
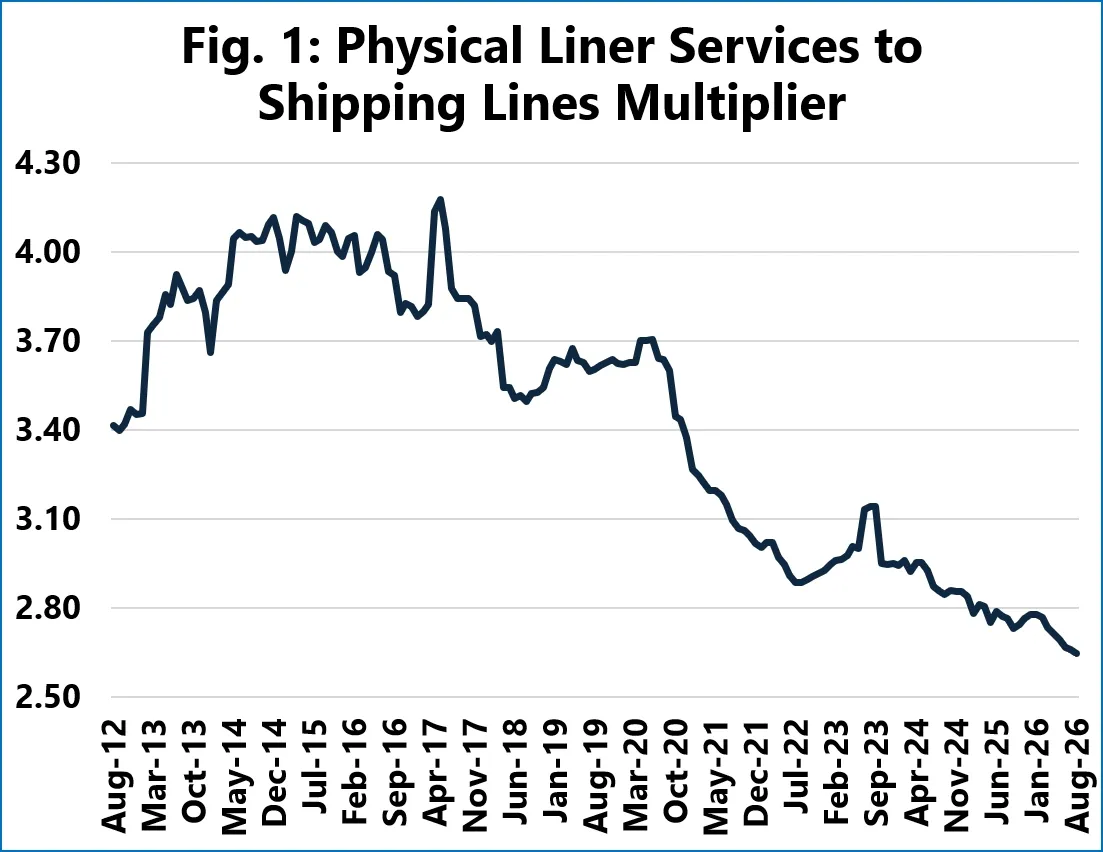
According to Sea-Intelligence data, the number of international container shipping services increased from around 250 in 2012–2013 to nearly 380 by late 2026. Meanwhile, the number of carriers offering space on each service has been trending downward.
Source: Sea-Intelligence
This trend is clearly reflected in the average number of carriers marketing space on each service. The figure stood at 4.12 carriers during 2014–2016, but had fallen to 2.65 by August 2026.
The decline suggests that carriers are becoming less reliant on arrangements in which multiple parties market space on the same service. Rather than depending as heavily on shared capacity, some carriers are taking greater control over service organization and operations, from capacity allocation to network planning.
However, a decline in capacity sharing does not mean that all carriers are moving toward independent operations. Cooperation agreements remain important in the container shipping industry, although the extent of collaboration varies by trade lane and carrier strategy.
If this trend continues, sailing schedules, port rotations and connections between services could become more differentiated. For shippers, these differences may make it easier to select services based on their actual operational characteristics rather than solely on the brands marketing them.
Overall, as the number of carriers offering space on each service declines while networks continue to expand, differences in sailing schedules, port rotations and service connections could become increasingly important factors in competition among shipping lines.
See more:
- Hapag-Lloyd to Adjust Six Asia–Europe Services Under Gemini Cooperation from November 2026
- Port of Rotterdam Container Throughput Remains Nearly Flat as Transshipment Volumes Fall 20%
- Strait of Hormuz Sees Further Attacks as Two Commercial Vessels Sink
- Port of Oakland Signals Recovery as September Container Throughput Rises 5.4%
- Mega-Container Vessels Return to the Suez Canal Despite Persistent Red Sea Risks
- Ship Recycling Activity Drops to More Than 50-Year Low as Global Fleet Faces Rapid Aging
- ClarkSea Index Sets Fifth Consecutive Record as Daily Vessel Earnings Reach $84,951
- Ocean Shipping Disruptions and Tariff Uncertainties Drive Incremental Air Freight Demand in Q4
- MSC and ONE to Continue Ipanema Service Under New VSA from April 2027
- Around 12% of Global Containership Capacity Affected by Port Congestion
- COSCO schedules: Vietnam - North America in Oct 2026
- COSCO updates Vietnam-North Europe sailing schedules in Oct 2026
- SITC updates Vietnam-Intra Asia sailing schedules in Oct 2026
Source: Phaata.com (According to Sea-Intelligence)
► Find Better Freight Rates & Logistics Service Providers!


Featured News
- Hapag-Lloyd applies Peak Season Surcharge from East Asia to USA and Canada
- The world\'s largest container ships MSC Irina and MSC Loreto floated
- MSC (Mediterranean Shipping Company) - The world\'s leading container shipping lines
- Information you need to know about Maersk Line
- Top 10 export and import goods between Vietnam - Philippines in the first 5 months of 2020

 Market News
See more

 HOT PROMO
See more
507
 FCL
 6 Days
 Freight cost

CÔNG TY CỔ PHẦN TIẾP VẬN INTERCARGO
1240
FCL
5 Days
Freight cost
CÔNG TY TNHH VẬN CHUYỂN QUỐC TẾ N.B.L
2895
FCL
20 Days
Freight cost

N.B.L INTERNATIONAL TRANSPORT CO., LTD
4411
FCL
21 Days
Freight cost
MG LOGISTICS JSC
5758
FCL
28 Days
Freight cost

CÔNG TY TRÁCH NHIỆM HỮU HẠN DT LOGISTICS (VN)
Why do thousands of businesses trust Phaata?
USERS/MONTH
LOGISTICS COMPANIES
REQUEST FOR QUOTEŚ
QUOTATIONS
VIETNAM LOGISTICS COMMUNITY
5 Steps to Get the Best Quote
Find a price quickly/Send a RFQ
Compare multiple options
Contact for Further Consultation
Negotiating prices/services
Management & rating
 Freight rates
Sea freight
- FCL
See more
25
20
Days Direct
- ₫54,778,410 / 20'RF
- ₫90,503,460 / 40'RQ
GIA LINH LOGISTICS SERVICES CO., LTD. (G LINK Logistics)
197
 436
56
Days Transit
- ₫187,887,300 / 20'GP
- ₫234,462,180 / 40'GP
- ₫234,462,180 / 40'HQ

CÔNG TY TNHH TIẾP VẬN TOÀN CẦU KM
430
5
Days Direct
- ₫16,312,500 / 20'GP
CÔNG TY CỔ PHẦN TIẾP VẬN INTERCARGO
1,331
7
Days Direct
- ₫23,816,700 / 20'GP
- ₫39,694,500 / 40'GP
CÔNG TY TNHH VẬN CHUYỂN QUỐC TẾ N.B.L
Sea freight
- LCL
See more
523
 1,100
5
Days Direct
- ₫26,463 /cbm

CÔNG TY TNHH T&M FORWARDING - CHI NHÁNH HÀ NỘI
2,553
3
Days Direct
- Refund ₫926,205 /cbm
CÔNG TY CỔ PHẦN GIAO NHẬN VẬN TẢI HỒNG SƠN
3,104
3,461
3
Days Direct
- ₫132,315 /cbm
CÔNG TY TRÁCH NHIỆM HỮU HẠN DT LOGISTICS (VN)
 Air freight
- General cargo
See more
3,710
1
Days Direct
- 46,310 ₫/kg
N.B.L INTERNATIONAL TRANSPORT CO., LTD
4,955
1
Days Direct
- 161,424 ₫/kg
CÔNG TY CỔ PHẦN GIAO NHẬN VẬN TẢI HỒNG SƠN
7,635
10
Days Transit
- 264,630 ₫/kg

Phoenix Logistics Vietnam - chi nhánh TP. Hồ Chí Minh (Phoenix International Forwarding Vietnam )
9,255
1
Days Direct
- 185,241 ₫/kg

CÔNG TY TNHH THƯƠNG MẠI VÀ DỊCH VỤ FASTRANS
9,377

 Rail freight
- FCL
See more
5,034
5
Days Direct
- ₫44,987,100 / 40'HQ
- ₫44,987,100 / 45'HQ

CÔNG TY TNHH PHƯỚC TÁ
7,360
3
Days Direct
- ₫15,083,910 / 40'HQ
CÔNG TY CỔ PHẦN VẬN TẢI VÀ THƯƠNG MẠI ĐƯỜNG SẮT
17,497
7
Days Direct
- ₫48,956,550 / 20'GP

Công ty TNHH T&M Forwarding
16,213
5
Days Direct
- ₫7,145,010 / 20'GP
ASIAN EXPRESS LINE VIETNAM ( AEL VIET NAM )
10,394
10
Days Direct
- ₫9,262,050 / 20'GP

CÔNG TY CỔ PHẦN LOGISTICS QUỐC TẾ V&T
 Road freight
- FCL
See more
882
 7,126
1
Day
- ₫28,000,000 / 20'GP
- ₫28,000,000 / 40'GP

CÔNG TY TNHH THƯƠNG MẠI DỊCH VỤ VÀ KHO VẬN VIETTEL POST - TTC
108,241
2
Day
- ₫6,500,000 / 40'RF
- ₫6,500,000 / 40'RQ
- ₫6,500,000 / 45'RQ

CÔNG TY CP PROSHIP
 Premium
176,796
1
Day
- ₫18,997,200 / 20'GP
- ₫18,997,200 / 40'GP

CÔNG TY CỔ PHẦN GIAO NHẬN VẬN TẢI CON ONG
265,341
3
Day
- ₫32,000,000 / 20'GP
- ₫64,000,000 / 40'GP
- ₫64,000,000 / 40'HQ
- ₫64,000,000 / 45'HQ

Công ty Cổ phần phát triển thương mại Thuận Đạt Việt Nam


