


Monday, 06/04/2026, 11:29 (GMT +7)
 1135
International Shipping and Logistics Market Update Week 14/2026 | Phaata
International shipping and logistics market update - Week 14/2026
Table of Contents
-
World Container Index Week 14/2026
-
Asia - North America Ocean Freight Rates
-
Asia - Europe Ocean Freight Rates
-
Northern America - Asia Ocean Freight Rates
-
Northern Europe - Asia Ocean Freight Rates
-
Conclusions and Recommendations by Phaata
1. World Container Index Week 14/2026
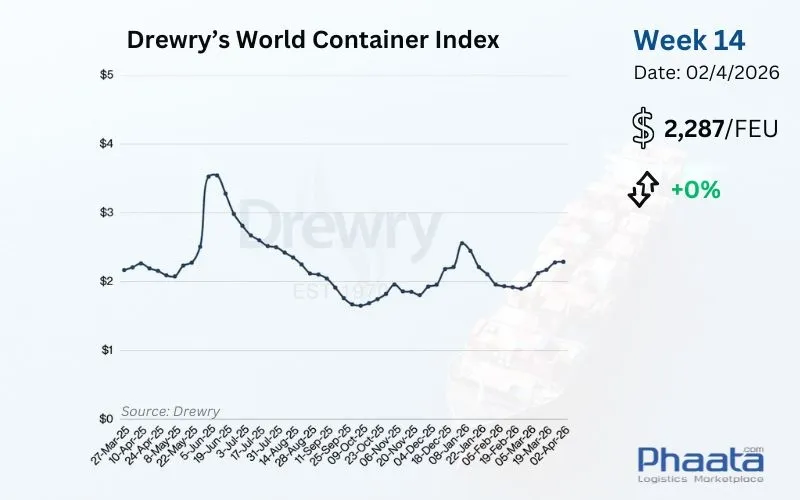
Drewry’s World Container Index (WCI) for Week 14/2026 (from March 30 to April 5, 2026) remained unchanged from the previous week, holding steady at $2,287/FEU. This marks the first week of leveling off following four consecutive weeks of increases.
Drewry's World Container Index Week 14/2026 (Photo: Phaata)
2. Asia-North America Ocean Freight Rates
Supply and Demand:
Demand Side:
Total import cargo volumes into the North American market recorded a recovery and actual growth throughout the second half of March.
Supply Side:
Carriers are stepping up the frequency of blank sailings throughout April. The focus of this capacity withdrawal is directly aimed at services discharging on the US East Coast (USEC).
Operations:
Under the pressure of soaring bunker costs, carriers have been forced to implement additional unscheduled blank sailings. This operational tactic aims to consolidate existing cargo to optimize vessel utilization on active voyages.
Rate Developments:
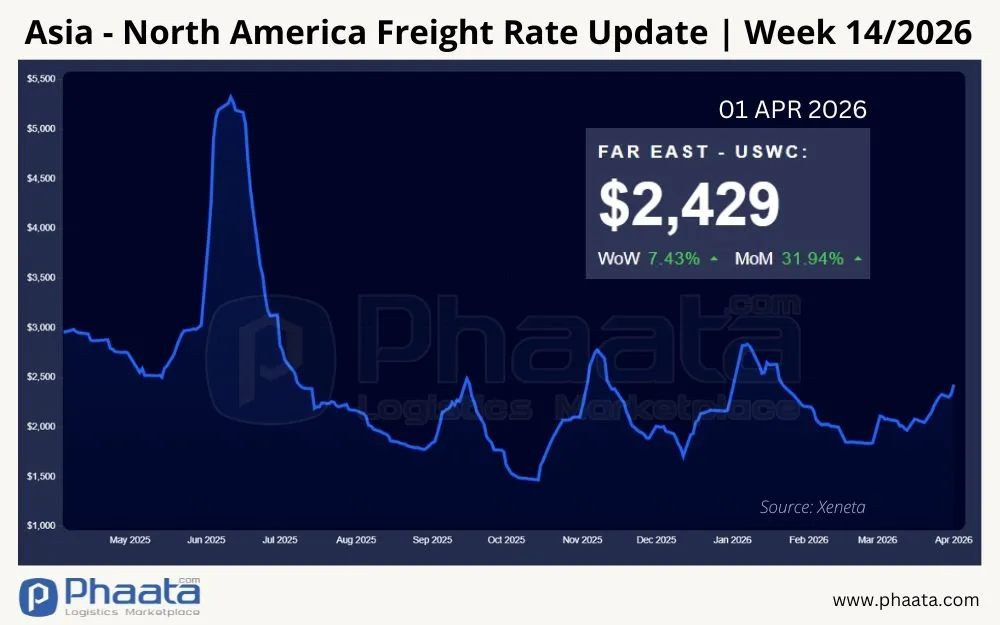
Ocean Freight rates from Asia to the North America West Coast in Week 14/2026 increased by 7.43% week-on-week, reaching $2,429/FEU. This rate is up 31.94% month-on-month, according to Xeneta data.
Carriers continue to apply a raft of new surcharges:
General Rate Increase (GRI): Carriers officially enforced the first round of GRI surcharges starting April 1. The next round of rate hikes is slated to be implemented in the second half of April.
Emergency Bunker Surcharge (EBS): In tandem with the second GRI, carriers will apply an EBS to directly offset soaring marine fuel costs.
Intermodal Fuel Surcharge (IFS): To cope with the shock increase in diesel prices, some carriers have issued notices to collect an IFS applicable to intermodal movements connecting via rail or truck into the US inland. This IFS surcharge will officially take effect on April 16.
Peak Season Surcharge (PSS) Delayed: The simultaneous application of fuel surcharges (EBS and IFS) has pushed total transport costs in April to exceptionally high levels. Consequently, carriers are forced to push back the PSS implementation to late April, or even May 1, to avoid fierce backlash from the market.
Stay tuned to Phaata International Logistics Marketplace for in-depth and fast market updates.
Asia-North America Freight Rates | Week 14/2026 (Photo: Phaata.com)
US Tariff Updates:
1. Comprehensive Restructuring of Section 232 Tariffs (Steel, Aluminum, Copper) The US President has signed an executive order overhauling the calculation method and collection rates for Section 232 tariffs on metals and derivative products. This policy officially takes effect on April 6, 2026, creating massive volatility in the Cost of Goods Sold (COGS):
Fundamental change in tax basis: The new tariff rate will be calculated on the full customs value of the finished product, rather than just the value of the metal content (steel, aluminum, copper) as previously done. This will multiply import costs exponentially.
General Tariff Rates:
-
25% tariff: Applied to steel, aluminum, and copper derivatives (listed in Annex I of the Order).
-
50% tariff (flat rate): Applied to the majority of metal items under Chapters 72 through 76 of the HTSUS. (Note: A wide range of products under Chapters 1-71 have been excluded from the derivative tariff list).
Preferential Rates by Origin and Function:
-
15% (applicable through 2027): Reserved for industrial equipment with high metal content and power grid equipment. (This 15% rate is inclusive of the Most Favored Nation - MFN tariff).
-
10%: Reserved for finished goods processed outside the US but utilizing 100% US-origin metal raw materials.
-
UK Origin Goods: Metal smelted/cast in the UK is subject to a 25% tariff (down from 50%); derivative products cast in the UK are subject to a 15% tariff (down from 25%).
Tightened Duty Drawback: Businesses are only permitted to claim duty drawback if the goods originated from, and were smelted/cast in, countries holding formal trade agreements with the United States.
2. Initiation of Section 232 Tariffs on the Pharmaceutical Industry The US government is officially utilizing Section 232 to intervene in the global pharmaceutical supply chain. The implementation roadmap will begin after 120 days for major corporations and 180 days for small-scale enterprises:
Punitive Tariff Group (100%): A 100% tariff applies to patented drugs manufactured by companies not participating in the Most Favored Nation (MFN) drug pricing agreement.
Incentives and Reshoring Policies:
-
Enterprises reshoring production lines back to the US enjoy a temporary tariff rate of 20% (which will revert to 100% on April 2, 2030).
-
Enterprises reshoring production to the US AND accepting the MFN pricing agreement will enjoy a 0% tariff rate throughout the factory construction process.
Regional Preferences: Products from Japan, the EU, South Korea, and the Switzerland/Liechtenstein bloc face a 15% tariff. Products from the UK face a 10% tariff. (All are eligible for the Drawback regime).
3. IEEPA Refund Operations (CAPE System) - Declaration Risk Warning Customs and Border Protection (CBP) expects to launch Phase 1 of the automated IEEPA refund system (CAPE) on April 20, 2026. However, CBP has announced a series of technical limitations that importers must pay special attention to:
Entries Excluded from Phase 1 (No automatic refund):
-
Entries pending Reconciliation or falling under Type 09.
-
Entries currently being used to file a Duty Drawback claim.
-
Entries with an Open Protest status.
-
Entries filed outside the ACE system or lacking a liquidated status in ACE.
-
Entries involving Anti-Dumping/Countervailing Duties (AD/CVD) pending liquidation instructions from the Commerce Department.
Processing Scope of Phase 1: The system will only automatically process unliquidated entries or those within the 90-day window where CBP holds the right to voluntary reliquidation. Finally liquidated entries must wait for Phase 2 of the system.
Immediate Action Directives:
-
File Protests: Regardless of whether the entry is excluded from Phase 1, the documentation department MUST file a Protest to maintain the entry's valid legal status.
-
Set up ACH: Immediately declare bank account information in the ACE system to receive Direct Deposits.
-
Audit Data: Clearly segregate IEEPA tariffs (refundable) and Section 232 tariffs (non-refundable) on the same entry to avoid declaration errors when filing through the CAPE system.
4. Expansion of the Section 232 Auto Parts Tariff List
Process: The US Commerce Department will open the portal to receive requests for adding new HS codes to the Section 232 auto parts tariff list from April 1 through April 14, 2026.
Lead Time Warning: Based on historical data from the steel industry, the time from the portal's closure until the new tariffs officially take effect is approximately 3.5 months. Importers of auto parts need to finalize orders early and push them into production in Q2 to bypass the new tariff wave expected around mid-Q3.
Stay tuned to articles on the Phaata International Logistics Marketplace for rapid and in-depth market updates.
3. Asia-Europe Ocean Freight Rates
Supply and Demand:
Demand:
Consumption in the European market continues to linger at a low level due to bleak macroeconomic indicators. Specifically, the 2026 GDP growth forecasts for the two leading economies, Germany and France, are both under 1%, directly depressing import demand and inventory replenishment.
Supply:
The continuous delivery of newbuild vessels to carriers should ostensibly have created a state of structural oversupply. However, the fact that 100% of vessels must maintain the Cape of Good Hope routing due to the Strait of Hormuz blockade has automatically absorbed and neutralized this entire excess capacity.
Operations:
The operational network is under disruptive pressure from extreme weather and chain-reaction congestion across all 3 critical nodes of the supply chain:
At Port of Loading (China): Dense fog has severely disrupted maritime operations at major ports like Shanghai, Ningbo, and Qingdao. This condition directly causes berth congestion and delays departure schedules.
At Transshipment Hub (Singapore): The Port of Singapore is enduring secondary congestion as it absorbs massive volumes of diverted transshipment cargo from the Middle East. Yard utilization has breached the 85% threshold, pushing vessel berthing wait times up to 1 to 1.5 days.
At Destination Ports (North Europe): Major hubs like Rotterdam and Antwerp are facing extremely high yard container densities. Bad weather combined with vessel bunching has sharply increased container dwell times for imports.
Equipment Cycle (Empty Containers): The detour around Africa prolongs the empty container turnaround cycle by multiple weeks compared to the norm. The inevitable fallout is the risk of a severe shortage of empty equipment for stuffing exports at Far East ports in the coming period.
Freight Rate Developments:
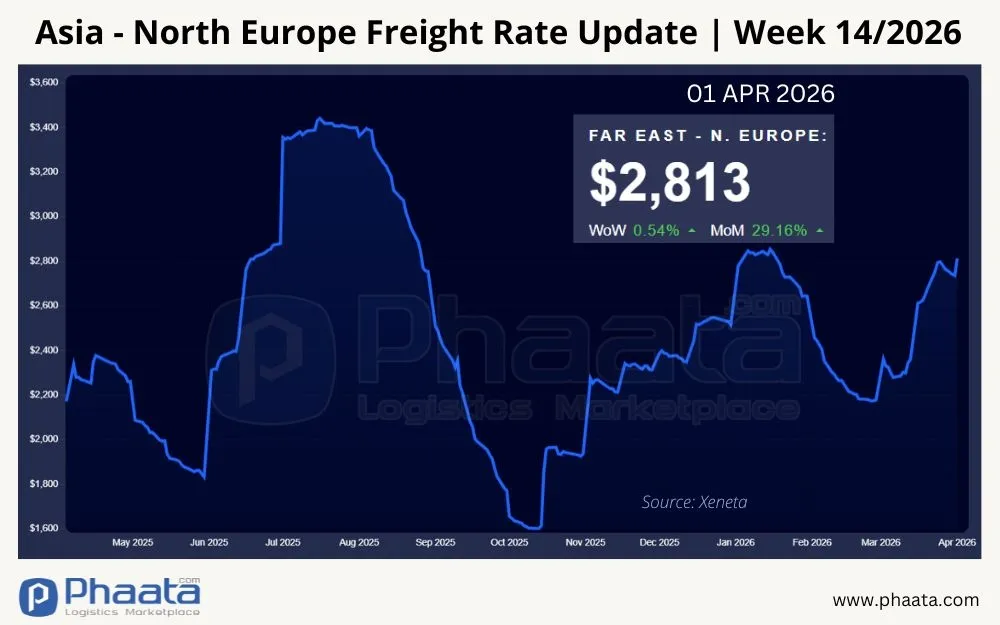
Ocean Freight rates from Asia to Europe in Week 14/2026 continued to increase slightly by 0.54% week-on-week, reaching $2,813/FEU. This rate is up 29.16% month-on-month, per Xeneta data.
Successfully Defending the Price Floor: Despite actual cargo volumes in the market remaining low, carriers successfully defended the baseline rate throughout March. This result was achieved through ironclad discipline in capacity control and the rigorous collection of surcharges related to the Middle East conflict.
April Pricing Environment: Heading into April, the market remains completely under carrier-dominated pricing. The primary momentum anchoring freight rates stems not from purchasing power, but from proactive blank sailing programs and cost pressures from the Middle East. Rate levels are forecast to remain stable and firmly anchored throughout the entirety of April.
Stay tuned to Phaata International Logistics Marketplace for in-depth and fast market updates.
Asia-Europe Freight Rates | Week 14/2026 (Photo: Phaata.com)
4. North America - Asia Ocean Freight Rates
Ocean Freight rates from North America (West Coast) to Asia in Week 14/2026 continued to increase slightly by 0.17% week-on-week, up to $582/FEU. This rate is down 5.21% month-on-month, according to Xeneta data.
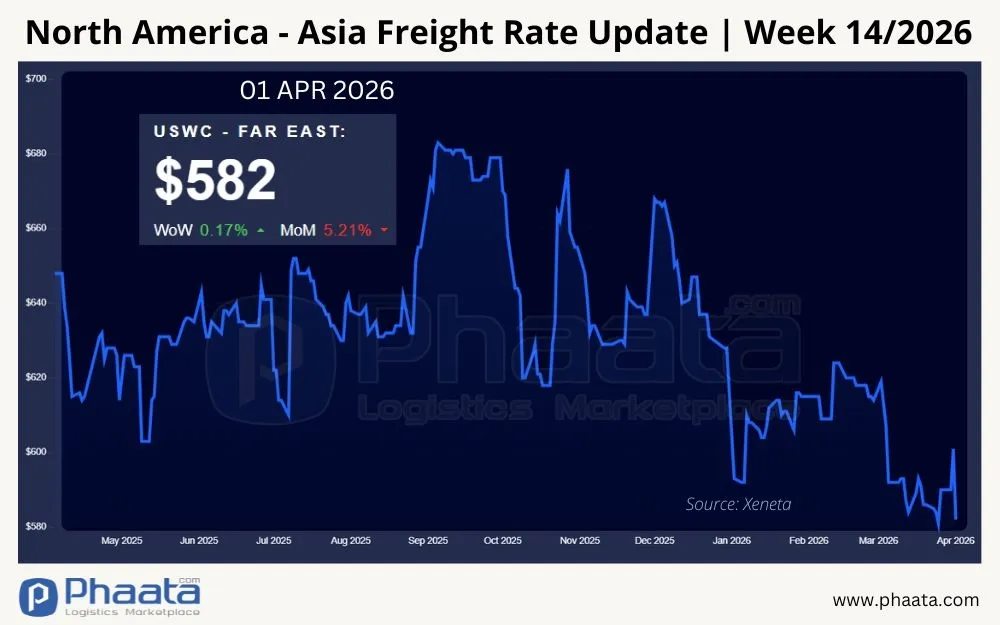
North America (West Coast) - Asia freight rates | Week 14/2026 (Photo: Phaata.com)
5. Northern Europe - Asia Ocean Freight Rates
Ocean Freight rates from North Europe to Asia in Week 14/2026 continued to surge sharply by 23.24% week-on-week, up to $228/FEU. This rate is up 62.86% month-on-month, per Xeneta data.
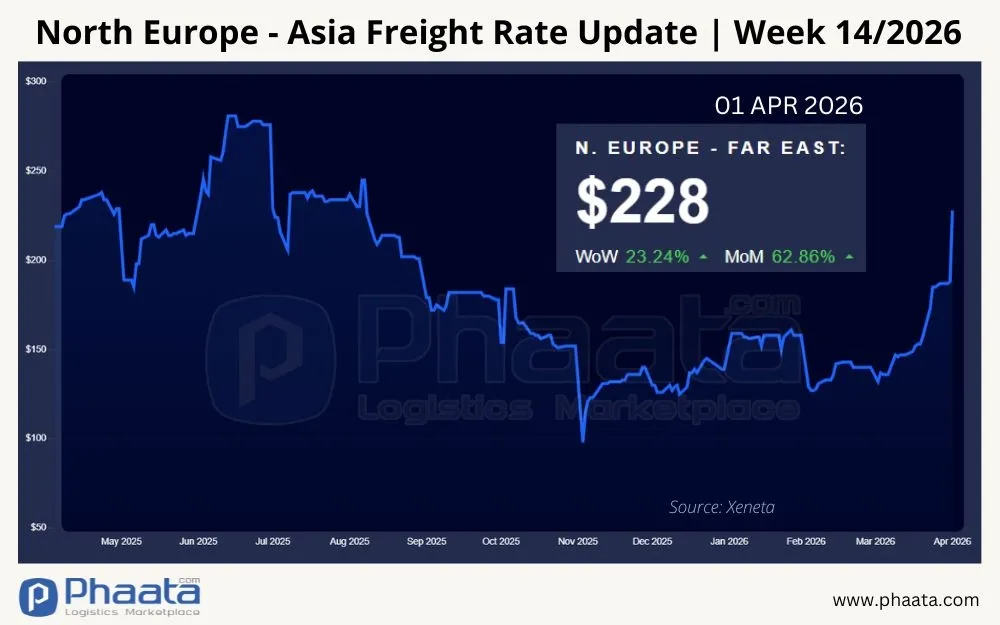
Container Freight rates from Northern Europe to Asia | Week 14/2026 (Photo: Phaata.com)
6. Conclusion and Recommendations from Phaata
The market in Week 14/2026 has established three concrete risks directly impacting global supply chain costs and schedules:
- Carrier-Dominated Pricing Market: Despite weakened purchasing power in Europe and only a mild recovery in North America, Asia-Europe rates (up 0.54%) and Asia-North America rates (up 7.43%) remain anchored at high levels. The sole driver is carriers tightening supply via blank sailings and imposing a matrix of surcharges (GRI, EBS, IFS). Current transport rates have decoupled from normal cargo supply and demand laws.
- Ruptured Equipment Turnaround Chain: The compounded impact of bad weather in China, secondary congestion in Singapore (yard density 85%), bottlenecks in North Europe, and the African detour is tying up massive quantities of containers. The risk of empty container shortages at Asian origin ports in the coming weeks is critically high.
- COGS Shock in the US Market: Altering the Section 232 calculation method (assessed on the full value of the finished product rather than metal content) will multiply the Landed Cost exponentially. Concurrently, the technical barriers of CAPE Phase 1 will block the automated IEEPA duty refund cash flow for many businesses unless manual interventions are made.
Recommendations from Phaata
Amidst a tightening market and rising legal costs, businesses must prioritize the following:
1. Logistics & Supply Chain Operations:
-
Equipment Priority Tactics: Shift negotiation priorities from "freight rates" to "guaranteed empty container release." The documentation department must lock in bookings and secure empty container releases at least 3 weeks in advance. Prioritize utilizing Named Account Contracts (NAC) that include Space & Equipment Guarantee clauses.
-
Isolate US Inland Surcharges: For shipments delivered deep into the US inland via rail/truck, it is mandatory to demand that Forwarders provide the original breakdown sheet from the carrier regarding the Intermodal Fuel Surcharge (IFS) effective April 16. Do not accept the IFS being lumped into the Ocean Freight to protect cost auditing accuracy.
-
Update Estimated Lead Times: Directly add 14 days to the committed delivery schedule on contracts for European-bound shipments to offset vessel anchorage times in the fog-affected Shanghai/Ningbo region and berthing wait times in Singapore.
2. Customs and Finance Operations (US Market):
-
Recalculate Cost of Goods Sold (COGS) Immediately: The finance and import-export departments must audit the entire portfolio of goods containing steel, aluminum, and copper. Immediately apply the Section 232 formula based on the full customs value of the finished product to establish new pricing for shipments arriving at US ports from April 6 onward.
-
Directive for Widespread Protest Filings: Based on CBP's exclusion list, Phase 1 of the CAPE system will deny automatic refunds for entries pending reconciliation, Drawback entries, or entries not updated in ACE. Customs brokers MUST manually file Protests for 100% of IEEPA entries to lock in their legal status and preserve the right to receive refunds.
-
Prepare Auto Parts Production Plans: The window for accepting new HS codes subject to Section 232 tariffs closes on April 14. Given the precedent of a 3.5-month process, importers of auto parts must accelerate production schedules and export goods squarely within Q2/2026 to dodge the new tariff wave projected to hit mid-Q3.
Stay tuned to articles on Phaata.com or Phaata fanpage for rapid and in-depth market updates.
Find Freight Rates Here
Find Logistics Companies Here
See more:
- Tariffs and Demand Reshape Cold Chain Strategies
- US Court Rules in Favor of FMC: Clamping Down on Ocean Carriers' Unreasonable Refusals of Vessel Space
- Ripple Effect: Middle East Crisis Reshapes Global Aviation Logistics and Supply Networks
- Fleet Greening Strategy: Nantong Cosco and Norsepower Strengthen Global Cooperation on Rotor Sail Technology
- COSCO updates Vietnam-Intra Asia sailing schedules in Apr 2026
- Gulf Conflict Update: Iran Opens 'Controlled Corridor' at the Strait of Hormuz, Supply Chains Remain Strained
- Qatar Airways Cargo Gradually Resumes Global Operations
- COSCO schedules: Vietnam - North America in Apr 2026
- SITC updates Vietnam-Intra Asia sailing schedules in Apr 2026
- International Shipping and Logistics Market Update Week 13/2026 | Phaata
- Shipping Line ONE Acquires 30% Stake in Key Laem Chabang Port, Thailand
- CMA CGM Implements Peak Season Surcharges on Mauritius and West Africa Routes
- Hapag-Lloyd Announces General Rate Increase (GRI) on South America Route
- COSCO SHIPPING Resumes Bookings to the Middle East via Multimodal Transport Network
- Strategic Port of Salalah (Oman) Suspends Operations Following UAV Attack
- EUNAVFOR ASPIDES Warning: Threat of Attacks on Commercial Shipping in the Red Sea Shows Signs of Escalation
- Geopolitical 'Undercurrents' and the Restructuring Race Reshaping the Global Shipping Map
Source: Phaata - Vietnam's First International Logistics Marketplace
► Find Better Freight Rates & Logistics Service Providers!


Featured News
- Hapag-Lloyd applies Peak Season Surcharge from East Asia to USA and Canada
- The world\'s largest container ships MSC Irina and MSC Loreto floated
- MSC (Mediterranean Shipping Company) - The world\'s leading container shipping lines
- Information you need to know about Maersk Line
- Top 10 export and import goods between Vietnam - Philippines in the first 5 months of 2020

 Market News
See more





 HOT PROMO
See more
70
 FCL
 30 Days
 Freight cost

CÔNG TY TNHH PEGASHIP
1362
FCL
45 Days
Freight cost

Compass Logistics
 Premium
2980
FCL
30 Days
Freight cost

CÔNG TY TNHH INTERNATIONAL LOGISTICS GLORY (VIỆT NAM)
4529
FCL
3 Days
Freight cost

Công ty TNHH Giao nhận vận chuyển Quốc tế Trường Hải - THILOGI
Premium
4379
FCL
10 Days
Freight cost
CÔNG TY TNHH THƯƠNG MẠI VÀ DỊCH VỤ GREEN DRAGON VIỆT NAM
Why do thousands of businesses trust Phaata?
USERS/MONTH
LOGISTICS COMPANIES
REQUEST FOR QUOTEŚ
QUOTATIONS
VIETNAM LOGISTICS COMMUNITY
5 Steps to Get the Best Quote
Find a price quickly/Send a RFQ
Compare multiple options
Contact for Further Consultation
Negotiating prices/services
Management & rating
 Freight rates
Sea freight
- FCL
See more
44
5
Days Direct
- ₫39,694,500 / 40'HQ
CÔNG TY TNHH VẬN CHUYỂN QUỐC TẾ TÂN TOÀN CẦU
124
7
Days Direct
- ₫40,223,760 / 40'HQ

CÔNG TY TRÁCH NHIỆM HỮU HẠN DT LOGISTICS (VN)
149
 200
25
Days Transit
- ₫30,432,450 / 20'GP
- ₫38,371,350 / 40'GP
- ₫38,371,350 / 40'HQ
- ₫38,371,350 / 45'HQ

T.H.I GROUP VIỆT NAM
199
8
Days Direct
- ₫34,087,300 / 40'HQ

CÔNG TY TNHH VẬN TẢI VÀ TIẾP VẬN TOÀN CẦU
Sea freight
- LCL
See more
1,941
4
Days Direct
- ₫26,463 /cbm

CÔNG TY TNHH IEC EXPRESS (VIỆT NAM)- CHI NHÁNH HÀ NỘI
3,009
5
Days Direct
- ₫26,463 /cbm

CHI NHÁNH TẠI THÀNH PHỐ HỒ CHÍ MINH - CÔNG TY CỔ PHẦN MG LOGISTICS
3,638
8
Days Direct
- Refund ₫2,362,500 /cbm

CÔNG TY CỔ PHẦN TIẾP VẬN INTERCARGO
4,202
4
Days Direct
- ₫26,463 /cbm

CÔNG TY CỔ PHẦN GIAO NHẬN VẬN TẢI MỸ Á (ASL LOGISTICS)
4,261

 Air freight
- General cargo
See more
1,012
10
Days Transit
- 264,630 ₫/kg

Phoenix Logistics Vietnam - chi nhánh TP. Hồ Chí Minh (Phoenix International Forwarding Vietnam )
1,734
1
Days Direct
- 185,241 ₫/kg

CÔNG TY TNHH THƯƠNG MẠI VÀ DỊCH VỤ FASTRANS
5,225
 4,914
8
Days Transit
- 224,936 ₫/kg

CÔNG TY TNHH SEA GLOBAL VIỆT NAM
2,769
1
Days Direct
- 502,797 ₫/kg

CÔNG TY TNHH VẬN TẢI QUỐC TẾ GIA PHÚ
 Rail freight
- FCL
See more
778
5
Days Direct
- ₫26,463,000 / 40'HQ
- ₫26,463,000 / 45'HQ

CÔNG TY TNHH PHƯỚC TÁ
1,110
3
Days Direct
- ₫6,324,657 / 40'HQ

CÔNG TY CỔ PHẦN VẬN TẢI VÀ THƯƠNG MẠI ĐƯỜNG SẮT
10,425
7
Days Direct
- ₫48,956,550 / 20'GP

Công ty TNHH T&M Forwarding
9,797
5
Days Direct
- ₫7,145,010 / 20'GP

ASIAN EXPRESS LINE VIETNAM ( AEL VIET NAM )
8,208
10
Days Direct
- ₫9,262,050 / 20'GP

CÔNG TY CỔ PHẦN LOGISTICS QUỐC TẾ V&T
 Road freight
- FCL
See more
42,618
1
Day
- ₫6,868,686 / 20'OT
- ₫6,868,686 / 40'OT
- ₫6,868,686 / 40'OT HQ

CÔNG TY TNHH LIÊN VẬN QUỐC TẾ SHINING OCEAN VIỆT NAM
99,811
2
Day
- ₫6,500,000 / 40'RF
- ₫6,500,000 / 40'RQ
- ₫6,500,000 / 45'RQ

CÔNG TY CP PROSHIP
Premium
170,081
1
Day
- ₫18,997,200 / 20'GP
- ₫18,997,200 / 40'GP

CÔNG TY CỔ PHẦN GIAO NHẬN VẬN TẢI CON ONG
262,417
3
Day
- ₫32,000,000 / 20'GP
- ₫64,000,000 / 40'GP
- ₫64,000,000 / 40'HQ
- ₫64,000,000 / 45'HQ

Công ty Cổ phần phát triển thương mại Thuận Đạt Việt Nam
283,137


