


Tuesday, 07/04/2026, 15:00 (GMT +7)
 530
Ocean Freight Market Stalls: Overcapacity Outweighs the 'Hormuz Shock'
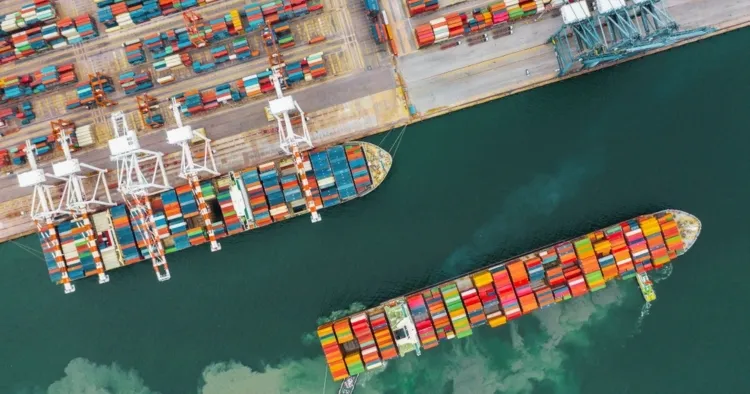
Spot container freight rates on the major East-West trade lanes largely moved sideways this week. The root cause is structural overcapacity and an uneven demand recovery, which have thwarted ocean carriers' attempts to push rates higher.
The Divergent Picture on the Asia-Europe Trade
This week’s World Container Index (WCI) from research consultancy Drewry indicates that spot rates on the Trans-Pacific and Asia-Europe trades appear to have largely stabilized after rebounding from the Middle East conflict shock.
Specifically, on the Shanghai-Rotterdam leg, the WCI remained flat week-on-week at $2,543/FEU (40-foot equivalent unit). Meanwhile, the Shanghai-Genoa leg edged up slightly by 2%, settling at $3,529/FEU.
This indicates that the new FAK (Freight All Kinds) rates introduced by carriers on Wednesday (April 1) have not yet truly taken effect. For instance, CMA CGM implemented a new FAK rate of $3,500/FEU for shipments from Asia to Northern Europe, but this level remains roughly $1,000/container higher than the actual prevailing market rates.
According to analysts at Linerlytica, the issue lies in the fact that carriers on the Asia-Europe trade seem to be prioritizing volume over price. They noted that Asia-Europe rates continue to fluctuate as carriers announce general rate increases, only to undercut themselves shortly after when utilization rates fail to support the new pricing. Maersk continues to offer rates below the market average through spot freight discounts, despite earlier attempts at minor rate hikes. This pricing trend is highly likely to repeat itself throughout April.
Drewry also noted that only four blank sailings have been announced for the coming week. Therefore, barring a sudden surge in demand during the Easter holidays, this sideways trend is likely to persist.
Trans-Pacific Rates and Global Impacts
A similar situation is playing out on the Trans-Pacific trade, where the WCI's Shanghai-Los Angeles route dropped 1% to $2,663/FEU, while the Shanghai-New York leg increased 1% to $3,434/FEU.
However, looking at the broader picture, Xeneta’s short-term spot rate data reveals that shippers and forwarders have had to weather an approximate 30% surge in spot rates from late February to early April.
Peter Sand, Chief Analyst at Xeneta, observed that this disruption is global in nature: "Five weeks into the Strait of Hormuz closure and spot rates on every major East-West trade lane have risen sharply, showing this is a conflict with global repercussions for ocean supply chains."
"From Far East to North Europe and Mediterranean – trades with direct exposure to the Middle East disruption – spot rates are up 31% and 30% since the end of February."
He further emphasized that the risk has radiated far beyond the epicenter: "No shipper is insulated from financial or operational risk. Far East to US West Coast – a trade which transits the Pacific thousands of miles from the epicentre of conflict – has seen spot rates climb 29% since the end of February."
Xeneta’s short-term market average rate on the Far East to US West Coast trade stood at $2,430/FEU as of yesterday, with the East Coast at $3,382/FEU.
"Ultra-Short-Term" Pricing Strategy
Nevertheless, this upward momentum appears to have stalled, at least for this week. US West Coast-based forwarder Freight Right stated that shippers actively hunting for competitive rates "can still find rates as low as $1,650 from China to the US West Coast and $2,450 from China to the US East Coast."
According to Freight Right, sluggish US consumer demand - expected to be further exacerbated by rising gasoline prices - has prompted carriers to adopt an "ultra-short-term" pricing approach.
A company representative explained this mechanism as follows: "After attempting to jack up prices in late March, carriers saw volume vanish, forcing them to pivot and lower rates slightly to attract any available cargo."
"By only committing to seven-day rate windows, carriers are protecting themselves against sudden spikes in fuel or further drops in demand."
The Fuel Cost Puzzle and Upcoming "Levers"
However, the bunker cost puzzle is currently the biggest risk casting a shadow over the entire market. A slew of emergency bunker surcharges are expected to be officially activated in the coming weeks, and these quantum levels will almost certainly be pushed even higher in direct proportion to the duration of the conflict.
Despite this, Peter Sand noted that carriers still possess other tools to mitigate escalating costs, though few are appealing to shippers. Commenting on the bunker market, he shared: "Bunker fuel at Singapore - the world’s leading bunkering hub - remains available, with prices roughly double pre-crisis levels, but trending slowly downward after an initial spike of around 200%."
However, other regions are facing their own unique challenges: "Rotterdam prices continue rising, and ship-to-ship fuel transfers in the Far East are adding cost and complexity."
In response, emergency contingency measures are being weighed: "With no visible end to the crisis, however, carriers are almost certainly drawing up another set of contingency plans."
"The coming weeks will show whether slow steaming and alternative routing can hold the line, or whether blank sailings become the next lever carriers reach for."
See more:
- FMC Rejects Maersk's Emergency Bunker Surcharge Request for the Second Time
- CMA CGM Kribi: First Western Vessel to Transit Hormuz Amid US-Iran Tensions
- International Shipping and Logistics Market Update Week 14/2026 | Phaata
- PCS Logistics: “We Deliver Happiness” through Customer Experience
- Tariffs and Demand Reshape Cold Chain Strategies
- Port of Gothenburg Acquires Strategic Land: Poised to Trigger the Next Phase of Terminal Infrastructure Expansion
- US Court Rules in Favor of FMC: Clamping Down on Ocean Carriers' Unreasonable Refusals of Vessel Space
- Ripple Effect: Middle East Crisis Reshapes Global Aviation Logistics and Supply Networks
- Fleet Greening Strategy: Nantong Cosco and Norsepower Strengthen Global Cooperation on Rotor Sail Technology
- COSCO updates Vietnam-Intra Asia sailing schedules in Apr 2026
- Gulf Conflict Update: Iran Opens 'Controlled Corridor' at the Strait of Hormuz, Supply Chains Remain Strained
- Qatar Airways Cargo Gradually Resumes Global Operations
- COSCO schedules: Vietnam - North America in Apr 2026
- SITC updates Vietnam-Intra Asia sailing schedules in Apr 2026
Source: Phaata.com (According to gCaptain)
► Find Better Freight Rates & Logistics Service Providers!


Featured News
- Hapag-Lloyd applies Peak Season Surcharge from East Asia to USA and Canada
- The world\'s largest container ships MSC Irina and MSC Loreto floated
- MSC (Mediterranean Shipping Company) - The world\'s leading container shipping lines
- Information you need to know about Maersk Line
- Top 10 export and import goods between Vietnam - Philippines in the first 5 months of 2020

 Market News
See more





 HOT PROMO
See more
75
 FCL
 30 Days
 Freight cost

CÔNG TY TNHH PEGASHIP
1372
FCL
45 Days
Freight cost

Compass Logistics
 Premium
2990
FCL
30 Days
Freight cost

CÔNG TY TNHH INTERNATIONAL LOGISTICS GLORY (VIỆT NAM)
4540
FCL
3 Days
Freight cost

Công ty TNHH Giao nhận vận chuyển Quốc tế Trường Hải - THILOGI
Premium
4386
FCL
10 Days
Freight cost
CÔNG TY TNHH THƯƠNG MẠI VÀ DỊCH VỤ GREEN DRAGON VIỆT NAM
Why do thousands of businesses trust Phaata?
USERS/MONTH
LOGISTICS COMPANIES
REQUEST FOR QUOTEŚ
QUOTATIONS
VIETNAM LOGISTICS COMMUNITY
5 Steps to Get the Best Quote
Find a price quickly/Send a RFQ
Compare multiple options
Contact for Further Consultation
Negotiating prices/services
Management & rating
 Freight rates
Sea freight
- FCL
See more
47
5
Days Direct
- ₫39,694,500 / 40'HQ
CÔNG TY TNHH VẬN CHUYỂN QUỐC TẾ TÂN TOÀN CẦU
129
7
Days Direct
- ₫40,223,760 / 40'HQ

CÔNG TY TRÁCH NHIỆM HỮU HẠN DT LOGISTICS (VN)
153
 202
25
Days Transit
- ₫30,432,450 / 20'GP
- ₫38,371,350 / 40'GP
- ₫38,371,350 / 40'HQ
- ₫38,371,350 / 45'HQ

T.H.I GROUP VIỆT NAM
200
8
Days Direct
- ₫34,087,300 / 40'HQ

CÔNG TY TNHH VẬN TẢI VÀ TIẾP VẬN TOÀN CẦU
Sea freight
- LCL
See more
1,943
4
Days Direct
- ₫26,463 /cbm

CÔNG TY TNHH IEC EXPRESS (VIỆT NAM)- CHI NHÁNH HÀ NỘI
3,014
5
Days Direct
- ₫26,463 /cbm

CHI NHÁNH TẠI THÀNH PHỐ HỒ CHÍ MINH - CÔNG TY CỔ PHẦN MG LOGISTICS
3,643
8
Days Direct
- Refund ₫2,362,500 /cbm

CÔNG TY CỔ PHẦN TIẾP VẬN INTERCARGO
4,205
4
Days Direct
- ₫26,463 /cbm

CÔNG TY CỔ PHẦN GIAO NHẬN VẬN TẢI MỸ Á (ASL LOGISTICS)
4,262

 Air freight
- General cargo
See more
1,014
10
Days Transit
- 264,630 ₫/kg

Phoenix Logistics Vietnam - chi nhánh TP. Hồ Chí Minh (Phoenix International Forwarding Vietnam )
1,738
1
Days Direct
- 185,241 ₫/kg

CÔNG TY TNHH THƯƠNG MẠI VÀ DỊCH VỤ FASTRANS
5,228
 4,915
8
Days Transit
- 224,936 ₫/kg

CÔNG TY TNHH SEA GLOBAL VIỆT NAM
2,769
1
Days Direct
- 502,797 ₫/kg

CÔNG TY TNHH VẬN TẢI QUỐC TẾ GIA PHÚ
 Rail freight
- FCL
See more
779
5
Days Direct
- ₫26,463,000 / 40'HQ
- ₫26,463,000 / 45'HQ

CÔNG TY TNHH PHƯỚC TÁ
1,113
3
Days Direct
- ₫6,324,657 / 40'HQ

CÔNG TY CỔ PHẦN VẬN TẢI VÀ THƯƠNG MẠI ĐƯỜNG SẮT
10,428
7
Days Direct
- ₫48,956,550 / 20'GP

Công ty TNHH T&M Forwarding
9,799
5
Days Direct
- ₫7,145,010 / 20'GP

ASIAN EXPRESS LINE VIETNAM ( AEL VIET NAM )
8,209
10
Days Direct
- ₫9,262,050 / 20'GP

CÔNG TY CỔ PHẦN LOGISTICS QUỐC TẾ V&T
 Road freight
- FCL
See more
42,620
1
Day
- ₫6,868,686 / 20'OT
- ₫6,868,686 / 40'OT
- ₫6,868,686 / 40'OT HQ

CÔNG TY TNHH LIÊN VẬN QUỐC TẾ SHINING OCEAN VIỆT NAM
99,817
2
Day
- ₫6,500,000 / 40'RF
- ₫6,500,000 / 40'RQ
- ₫6,500,000 / 45'RQ

CÔNG TY CP PROSHIP
Premium
170,087
1
Day
- ₫18,997,200 / 20'GP
- ₫18,997,200 / 40'GP

CÔNG TY CỔ PHẦN GIAO NHẬN VẬN TẢI CON ONG
262,421
3
Day
- ₫32,000,000 / 20'GP
- ₫64,000,000 / 40'GP
- ₫64,000,000 / 40'HQ
- ₫64,000,000 / 45'HQ

Công ty Cổ phần phát triển thương mại Thuận Đạt Việt Nam
283,139


