

Monday, 23/03/2026, 16:00 (GMT +7)
 2992
2026 Dry Bulk Market: Will the Growth Momentum Continue?
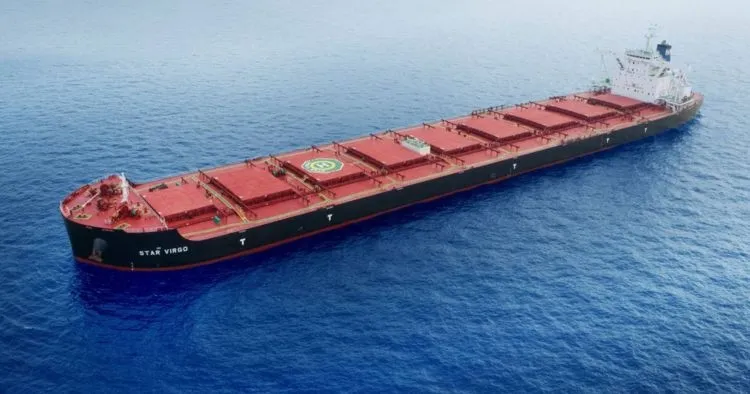
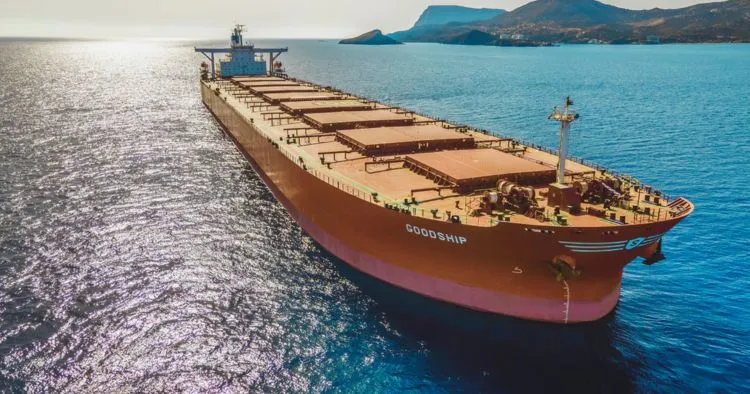
Photo: Star Bulk
Although recent geopolitical events in the Middle East have disrupted the global shipping industry, the dry bulk market has maintained relative stability compared to other segments. Overall, the direct drop in demand is largely being offset by a supply shortage, as many vessels are currently trapped west of the Strait of Hormuz. Even so, the secondary ripple effects impacting the fertilizer, grain, and coal markets could still yield significant consequences.
However, according to Maritime Strategies International's (MSI) Q1 dry bulk market report, the market is being driven by more fundamental dynamics. Any potential upside arising from these latest disruptions will merely compound an already highly positive picture for the dry bulk market this year.
Notably, even before Operation Epic Fury commenced in late February, dry bulk earnings were exceptionally strong. The Baltic Dry Index (BDI) averaged 1,906 points across January and February, compared to a mere 911 points during the same period in 2025. This robust start bears a striking resemblance to the unseasonal growth momentum recorded in early 2024.
Similar to early 2024, the current strength of the freight market is being spearheaded by the Capesize segment's outperformance. Robust Chinese import demand acts as the primary pillar, pushing port iron ore inventories to new record highs exceeding 150 million tons. Iron ore loading activity has also been extremely vibrant in Brazil, where the La Niña phenomenon has brought drier weather conditions, highly conducive to mining and logistics operations.
Concurrently, Australian iron ore exports have maintained their strength, bolstered by record-high throughput volumes at Pilbara, with export volumes in the first two months surging 13.2% year-on-year. Parallel to this, Guinean bauxite exports have entered their peak season, with January and February volumes climbing 25% year-on-year.
Capesize Supply Shrinks Due to Special Surveys
Robust demand is not the only factor underpinning the freight market. Foremost, low fleet growth is a pivotal element, particularly for the Capesize segment: only 7.2 million dwt (deadweight tonnage) of new Capesize vessels were delivered in 2025, equating to 1.9% of the total fleet, effectively offsetting the 1.1 million dwt that was scrapped.
A decline in commercial operating efficiency has also played a critical role, stemming from longer average voyage distances, increased port stays, and slower steaming speeds. Another crucial factor is the withdrawal of a substantial amount of tonnage from the market to undergo special periodic surveys - which has significantly impacted Capesize market strength in Q1.
MSI's analysis indicates that Q2 2026 will witness an increase in the actual effective capacity of the Capesize fleet as vessels that paused operations for surveys in Q1 begin returning to the market. Conversely, the supply growth trajectory for sub-Capesize fleets is trending towards significant expansion, with a projected schedule adding over 200 Panamax vessels to the fleet in 2026. This is the core rationale behind MSI's forecast that the earnings gap between Capesize and Panamax vessels will progressively widen this year.
Freight Market and Forward Contracts
In MSI's latest Q1 base case scenario, the widening disparity between Capesize and Panamax earnings is primarily shaped by a more optimistic outlook for Capesize freight rates. Simultaneously, the time charter earnings outlook across all dry bulk benchmark indices has also turned more positive compared to the previous update.
MSI is not the only entity taking an optimistic view of the dry bulk freight market. The monthly average data of the Capesize 5TC index, alongside the corresponding Forward Freight Agreement (FFA) forward curves from July 2025, December 2025, and February 2026, distinctly validate this sentiment.
Notably, the Q2 2026 Capesize contract was priced at $19,500/day in July 2025 but skyrocketed to $32,500/day by the end of February 2026, representing a 67% surge over an eight-month period. Although the forward curve has cooled slightly since its February peak, it remains hovering near $30,000/day for the remainder of this year.
Bright Spots from Iron Ore and Bauxite
Overall, dry bulk trade volumes are forecast to grow by approximately 1.9% year-on-year in the 2026 base case scenario. Furthermore, the impact of fleet expansion will be counterbalanced by an increase in dry bulk transport inefficiencies as voyage distances continue to lengthen and vessel speeds decrease this year.
MSI's latest Q1 2026 forecasting model suggests that deadweight-based demand will expand at just under 3% year-on-year in 2026, with the proportion heavily skewed towards Capesize vessels.
Ship Demolition Activity Slows Down
How will supply react to the more positive dry bulk demand outlook? Firstly, optimistic vessel earnings forecasts will stifle demolition activity. In the latest base case, scrapped tonnage is projected at a mere 4.5 million dwt in 2026 - essentially flat compared to 2025.
With anticipated newbuild deliveries reaching 42 million dwt this year, net fleet growth will hit a 14-year high of 37.6 million dwt, equating to a 3.6% year-on-year expansion rate. When adjusted for unavailable vessels and calculated on an annual average basis, this translates to a supply growth of 3.1%.
Because supply growth slightly edges out demand growth, MSI's base case predicts that the dry bulk fleet utilization rate in 2026 will weaken slightly, dropping from 88.1% in 2025 to 87.9% in 2026. Despite recent positive signals, this analysis does not conclude an overwhelmingly explosive boom for the rest of the year, although the diverging trends among segments are expected to generate highly differentiated earnings outcomes by vessel size.
See more:
- International Shipping and Logistics Market Update Week 12/2026 | Phaata
- Middle East Tensions: Maersk Imposes Global Fuel Surcharges
- Port Dispute: Panamanian President Rejects Hutchison's Accusations
- Hapag-Lloyd and India Establish a Strategic Maritime Cooperation Framework
- MSC Group Inks Deal to Acquire 50% Stake in Sinokor Maritime
- The Future of the ZIM Deal: Regulatory Hurdles for Hapag-Lloyd and Maersk's Contingency Plan
- Hormuz Shock: Over 204,000 TEUs at Risk of Being 'Trapped', Specter of Empty Container Shortages Returns to Asia
- CMA CGM's Pivot: Repatriating Fleet Under the French Flag as a Billion-Dollar US Pledge Remains in Limbo
- International Shipping and Logistics Market Update Week 11/2026 | Phaata
- February Tanker Market Review
- Asia-US Freight Rates Heat Up: US Considers Jones Act Waiver as FMC Scrutinizes Carrier Surcharges
- COSCO schedules: Vietnam - North America in Mar 2026
- SITC updates Vietnam-Intra Asia sailing schedules in Mar 2026
Source: Phaata.com (According to Splash247)
► Find Better Freight Rates & Logistics Service Providers!


Featured News
- Hapag-Lloyd applies Peak Season Surcharge from East Asia to USA and Canada
- The world\'s largest container ships MSC Irina and MSC Loreto floated
- MSC (Mediterranean Shipping Company) - The world\'s leading container shipping lines
- Information you need to know about Maersk Line
- Top 10 export and import goods between Vietnam - Philippines in the first 5 months of 2020

 Market News
See more

 HOT PROMO
See more
213
 FCL
 21 Days
 Freight cost
MG LOGISTICS JSC
1224
FCL
25 Days
Freight cost

N.B.L INTERNATIONAL TRANSPORT CO., LTD
1807
FCL
28 Days
Freight cost

CÔNG TY TRÁCH NHIỆM HỮU HẠN DT LOGISTICS (VN)
2433
FCL
28 Days
Freight cost

Công Ty TNHH Quanterm Logistics Vietnam
2502
FCL
33 Days
Freight cost

CÔNG TY TNHH TIẾP VẬN TOÀN CẦU KM
Why do thousands of businesses trust Phaata?
USERS/MONTH
LOGISTICS COMPANIES
REQUEST FOR QUOTEŚ
QUOTATIONS
VIETNAM LOGISTICS COMMUNITY
5 Steps to Get the Best Quote
Find a price quickly/Send a RFQ
Compare multiple options
Contact for Further Consultation
Negotiating prices/services
Management & rating
 Freight rates
Sea freight
- FCL
See more
203
3
Days Direct
- ₫15,877,800 / 20'GP
- ₫21,170,400 / 40'GP
- ₫21,170,400 / 40'HQ

Công ty TNHH Giao nhận vận chuyển Quốc tế Trường Hải - THILOGI
 Premium
23
4
Days Direct
- ₫5,557,230 / 20'GP
CÔNG TY TRÁCH NHIỆM HỮU HẠN DT LOGISTICS (VN)
21
3
Days Direct
- ₫6,086,490 / 40'HQ
CÔNG TY CỔ PHẦN GIAO NHẬN VẬN TẢI HỒNG SƠN
303
42
Days Transit
- ₫59,541,750 / 20'GP
- ₫91,297,350 / 40'HQ

Compass Logistics
Premium
262
25
Days Direct
- ₫179,948,400 / 40'HQ
CÔNG TY TNHH LIÊN VẬN QUỐC TẾ SHINING OCEAN VIỆT NAM
Sea freight
- LCL
See more
231
1,115
3
Days Direct
- ₫132,315 /cbm
CÔNG TY TRÁCH NHIỆM HỮU HẠN DT LOGISTICS (VN)
1,275
3
Days Direct
- ₫0 /cbm

CÔNG TY TNHH VẬN TẢI VÀ TIẾP VẬN TOÀN CẦU
2,588
4
Days Direct
- ₫0 /cbm
CÔNG TY CỔ PHẦN GIAO NHẬN VẬN TẢI HỒNG SƠN
3,635

 Air freight
- General cargo
See more
1,556
1
Days Direct
- 46,310 ₫/kg
N.B.L INTERNATIONAL TRANSPORT CO., LTD
2,147
1
Days Direct
- 161,424 ₫/kg
CÔNG TY CỔ PHẦN GIAO NHẬN VẬN TẢI HỒNG SƠN
5,076
10
Days Transit
- 264,630 ₫/kg

Phoenix Logistics Vietnam - chi nhánh TP. Hồ Chí Minh (Phoenix International Forwarding Vietnam )
6,809
1
Days Direct
- 185,241 ₫/kg

CÔNG TY TNHH THƯƠNG MẠI VÀ DỊCH VỤ FASTRANS
8,647

 Rail freight
- FCL
See more
2,916
5
Days Direct
- ₫44,987,100 / 40'HQ
- ₫44,987,100 / 45'HQ

CÔNG TY TNHH PHƯỚC TÁ
4,600
3
Days Direct
- ₫15,083,910 / 40'HQ
CÔNG TY CỔ PHẦN VẬN TẢI VÀ THƯƠNG MẠI ĐƯỜNG SẮT
15,018
7
Days Direct
- ₫48,956,550 / 20'GP

Công ty TNHH T&M Forwarding
13,807
5
Days Direct
- ₫7,145,010 / 20'GP
ASIAN EXPRESS LINE VIETNAM ( AEL VIET NAM )
9,716
10
Days Direct
- ₫9,262,050 / 20'GP

CÔNG TY CỔ PHẦN LOGISTICS QUỐC TẾ V&T
 Road freight
- FCL
See more
1,059
4
Day
- ₫5,000,000 / 40'GP

CÔNG TY CỔ PHẦN IGAP
3,383
1
Day
- ₫28,000,000 / 20'GP
- ₫28,000,000 / 40'GP

CÔNG TY TNHH THƯƠNG MẠI DỊCH VỤ VÀ KHO VẬN VIETTEL POST - TTC
5,198
4
Day
- ₫211,704 / 20'GP

CÔNG TY CỔ PHẦN KINH DOANH THƯƠNG MẠI VÀ DỊCH VỤ HỎA TỐC
104,773
2
Day
- ₫6,500,000 / 40'RF
- ₫6,500,000 / 40'RQ
- ₫6,500,000 / 45'RQ

CÔNG TY CP PROSHIP
Premium
173,503
1
Day
- ₫18,997,200 / 20'GP
- ₫18,997,200 / 40'GP

CÔNG TY CỔ PHẦN GIAO NHẬN VẬN TẢI CON ONG


